
Blogs
Navigating the Food Dryer Market: Strategic Shifts and Growth Horizons (2025–2032)
Market Landscape and Core Challenges
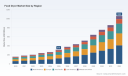
The global food dryer market has entered a phase of accelerated expansion, evolving from a mature processing niche into a strategic infrastructure component for food manufacturers, commercial kitchens, and emerging consumer wellness brands. Over the 2020–2025 period, the sector demonstrated consistent upward momentum, with revenue scaling steadily as drying technologies transitioned from utility-focused equipment to precision processing assets. Looking ahead to the 2026–2032 forecast horizon, the market is projected to follow a steep growth trajectory, driven by expanding applications in shelf-life extension, clean-label production, and decentralized food manufacturing. This progression signals more than incremental demand; it indicates a structural recalibration of how food processors approach moisture control, energy consumption, and product standardization.
Several macroeconomic and operational forces underpin this expansion. Food safety and traceability requirements continue to tighten across major trading blocs, pushing manufacturers toward equipment that can guarantee consistent moisture reduction and hygiene compliance. Simultaneously, the rise of alternative proteins, upcycled ingredients, and convenience formats has diversified the input materials requiring drying, creating demand for flexible, multi-stage drying architectures. Capacity investments in emerging processing hubs are also reshaping regional supply dynamics, while industrial digitization is redefining how drying lines are monitored, optimized, and maintained. Together, these forces are turning food dryers from passive processing tools into active nodes within broader food system resilience strategies.
Yet the sector is not moving through an unproblematic tailwind. The first major crossroads is regulatory and compliance complexity. Safety authorities now require stringent pre-heating protocols for meat and poultry-based dried products, alongside strict water activity thresholds for fruits and botanical ingredients. Equipment that cannot reliably demonstrate compliance with hygienic design standards, sanitation routines, or energy-efficiency mandates risks exclusion from global supply chains. Manufacturers and buyers alike must navigate divergent certification frameworks across jurisdictions, where organic certification, CE marking, and local GMP expectations may all apply simultaneously. This fragmentation increases testing, validation, and documentation costs, particularly for companies expanding across multiple markets.
The second challenge is the widening performance gap between equipment generations. Older convection-heavy lines often struggle to maintain uniform moisture removal across varied feedstock geometries, leading to inconsistent product quality and higher rework rates. In contrast, newer integrated systems leverage controlled airflow, multi-zone temperature profiling, and modular clean-in-place capabilities to improve repeatability. The challenge for operators is capital allocation: upgrading or replacing equipment requires clear ROI justification, especially when throughput gains are offset by higher initial investment and operator retraining. Companies that treat drying assets as long-term process enablers, rather than isolated purchases, are better positioned to manage this transition.
Food Dehydrators Market
A third pressure point lies in energy intensity and sustainability scrutiny. Drying remains one of the most energy-demanding unit operations in food processing, and efficiency expectations are rising from both regulators and downstream customers. Equipment that fails to align with emerging eco-design expectations or that lacks traceability for energy and utility consumption may face procurement disadvantages. For processors operating on thin margins, the balance between throughput, consistency, and operating cost has become a critical decision variable.
Key Growth Drivers
Technological Innovation and Process Precision
The market is being reshaped by a shift from single-function dryers to intelligent, modular drying systems. Advances in airflow control, multi-zone heating, and real-time monitoring are reducing variability across batches, which matters increasingly for products where flavor retention, texture, and shelf stability are tied directly to drying consistency. Digital integration is extending these gains. Process simulation and virtual modeling are being used to optimize spray and continuous drying configurations before physical deployment, helping operators reduce trial-and-error cycles and shorten commissioning timelines. At the equipment level, modular clean-in-place systems are becoming more prominent because they lower sanitation downtime and support frequent product changeovers in multi-use facilities. This trend is especially relevant for processors handling diverse feedstocks, where flexibility and hygiene assurance must coexist.
The practical implication is that drying technology is increasingly evaluated on total process value rather than unit price. Buyers are looking for systems that can reduce water activity predictably, maintain nutrient integrity where required, and integrate smoothly with upstream and downstream lines. Equipment that supports rapid sanitation, precise moisture endpoints, and adaptable tray or conveyor configurations is gaining preference in applications where product rotation is high or where specifications vary by client or region.
Policy and Regulatory Pressure as a Market Catalyst
Regulatory developments are functioning less as barriers and more as structural demand drivers. Safety guidance increasingly mandates specific pre-heating steps for animal-protein-based dried products and defines water activity thresholds for fruits, herbs, and other perishable inputs to suppress microbial growth. These requirements are not optional nuances; they determine whether a facility can legally ship product through major distribution channels. At the same time, equipment standards are tightening around hygienic design, sanitation compatibility, and energy performance. Manufacturers that align their drying systems with recognized GMP expectations, regional certification pathways, and eco-design principles are gaining smoother market access, while laggards face longer validation cycles and reduced buyer confidence.
For exporters and multi-site operators, the regulatory environment rewards standardization. Facilities that design drying processes around defensible safety parameters and documented equipment compliance can reduce audit friction, expand into new markets faster, and avoid costly last-minute retrofits. Conversely, companies relying on legacy configurations without clear compliance pathways face growing operational risk, particularly as procurement teams increasingly ask for sanitation and safety documentation during vendor evaluation.
Demand-Side Shifts Across Consumer and Commercial Segments
Demand is expanding beyond traditional industrial dehydration into adjacent use cases that were previously underserved. Consumer-facing interest in long-shelf-life snacks, dried produce, herbal ingredients, and specialty pet treats is encouraging smaller processors and brand builders to invest in compact or mid-scale drying capacity. At the same time, commercial kitchens, co-manufacturers, and regional food brands are adopting drying as a way to stabilize seasonal supply, reduce waste, and extend distribution range. This broadening demand base is creating a two-tier market dynamic: large industrial lines continue to anchor high-volume ingredient and powder production, while smaller, digitally controlled units are gaining relevance for specialty, batch-oriented, or locally branded products.
The commercial implication is that drying equipment is no longer a single procurement category. It now spans high-throughput industrial configurations for ingredient and protein processing, mid-capacity systems for snack and bakery production, and compact multi-tray units for herbs, fruits, and direct-to-consumer or local brand applications. Companies that can serve multiple tiers with appropriately scaled solutions are capturing demand that was previously fragmented across informal or semi-industrial channels.
Supply Chain, Cost Structure, and Capacity Realignment
Cost pressures are reshaping procurement and capacity strategies. Energy volatility, material availability, and labor constraints are encouraging processors to prioritize equipment that delivers faster ramp-up, lower downtime, and more predictable operating profiles. In parallel, regional capacity builds are influencing where drying assets are deployed. As processing moves closer to sourcing regions or to demand centers with favorable logistics, dryer lines must accommodate different feedstock qualities, ambient conditions, and utility profiles. This is pushing equipment suppliers and buyers toward modular designs that can be tuned for local operating environments rather than relying on one-size configurations.
The broader effect is a stronger emphasis on total cost of ownership. Depreciation alone is no longer the dominant procurement lens. Operators are weighing sanitation cycle length, cleaning compatibility, changeover speed, energy consumption per unit output, and serviceability. These variables often determine whether a system can sustain margin through fluctuating input costs or high-mix production schedules. In that context, drying equipment is increasingly evaluated as a throughput-and-compliance asset rather than a simple thermal device.
Competitive Landscape and Leading-Player Strategies
The competitive field is defined by a mix of established industrial equipment providers, application-focused manufacturers, and specialists serving commercial and compact drying segments. The market remains moderately concentrated, with a core group of larger players holding significant share, but its structure is not static. Differentiation is increasingly determined by application fit, process integration capability, sanitation efficiency, and the ability to offer defensible compliance pathways.
Industrial-scale players are reinforcing their positions by embedding drying into broader processing architectures. Companies supplying spray and continuous drying technologies are focusing on ingredient, dairy, and powder applications where consistency, throughput, and hygiene are paramount. Their strategic advantage lies in the ability to align drying with upstream formulation and downstream packaging or storage requirements, reducing line fragmentation and improving end-product repeatability. In this tier, competitive edge is increasingly tied to process engineering depth, service networks, and the capacity to support compliance documentation across multiple geographies.
A second cluster of competitors is anchored in fruit, vegetable, snack, and bakery drying. These manufacturers compete on configuration flexibility, multi-pass and static drying options, and the ability to handle delicate or shape-sensitive materials without compromising output quality. Their positioning often centers on specialized airflow designs, changeover adaptability, and equipment that can be integrated into continuous or semi-continuous production lines. For buyers in these categories, the focus is less on raw capacity and more on texture preservation, color retention, and dependable moisture endpoints across varied product runs.
Commercial Food Dehydrators Market
A third competitive layer serves commercial and compact dehydration needs, including multi-tray dehydrators, digital-controlled units, and high-capacity commercial drying spaces. These players are expanding functionality through improved controls, tray configurations, and product-change versatility. Their relevance is growing as smaller producers, local brands, and specialty operations seek professional-grade drying without committing to large industrial installations. In this segment, usability, sanitation practicality, and consistent performance across smaller batch sizes are key differentiators.
Recent product and process developments illustrate how competition is evolving. Modular clean-in-place systems have been introduced to improve sanitation efficiency on drying-related process equipment, reflecting an industry-wide push to reduce downtime and support frequent changeovers. Digital control enhancements and expanded tray configurations are broadening commercial drying capacity, while process optimization tools such as digital twin modeling are being applied to improve ingredient drying performance and reduce tuning time. In parallel, advances in continuous powder drying technologies are strengthening throughput and consistency for high-volume applications. These developments point to a common direction: competitors are seeking to win by lowering operational friction, improving repeatability, and making drying systems easier to validate and maintain.
The landscape is also susceptible to consolidation and selective entry. Larger players with integrated processing portfolios are well placed to acquire or partner with specialists in adjacent drying technologies, especially where hygiene, automation, or compliance support creates a meaningful barrier. At the same time, new entrants can still find opportunities by targeting underserved application niches, regional demand pockets, or compact-to-mid-scale commercial segments where service and usability matter as much as raw capacity. The likely trajectory is a hybrid market: concentrated leadership at the industrial end, continued fragmentation and specialization in mid-scale and commercial layers, and growing importance of suppliers who can bridge drying with broader process and compliance requirements.
Forward Trends and Commercial Opportunities
Precision, Modularity, and Process Integration as Default Expectations
Over the next three to five years, drying systems are likely to be judged increasingly on integration and precision rather than isolated capacity. Multi-zone control, modular sanitation design, and digital monitoring will become baseline expectations in applications where product variability is high or where facilities must process multiple feedstocks on shared lines. This creates an opportunity for equipment strategies that emphasize flexible capacity, predictable moisture endpoints, and easy documentation for safety and quality audits. Buyers who standardize around these capabilities can reduce rework, improve changeover economics, and strengthen market access for products that require demonstrable drying consistency.
PW Consulting Automotive & Machinery Research Center
Compliance-Linked Equipment Selection Gaining Procurement Weight
Safety and eco-design expectations are poised to become more central in sourcing decisions. Procurement teams are likely to place greater weight on equipment that can demonstrate hygienic design compatibility, manageable sanitation routines, and defensible energy performance. This trend favors vendors and operators who can provide clear compliance narratives and support multi-jurisdiction certification pathways. For exporters and multi-site processors, this is both a risk management and growth opportunity: standardized, well-documented drying processes can accelerate market entry and reduce the operational drag of repeated validation cycles.
Segmentation Between Industrial Scale and Agile Commercial Capacity Intensifying
The market is likely to see a stronger structural split between high-volume industrial drying and agile, smaller-scale capacity. Industrial lines will continue to evolve around ingredient, dairy, powder, and protein applications where throughput and repeatability dominate. At the same time, compact-to-mid-scale systems will expand as brands, co-manufacturers, and regional processors seek decentralized drying for seasonal supply, waste reduction, and product differentiation. This bifurcation creates a dual opportunity: industrial players can capture value through broader line integration and process services, while commercial-focused suppliers can grow by offering controllable, user-friendly systems that fit smaller footprints and varied product mixes.
Across these trends, the key commercial risk is overinvestment in non-adaptive configurations. Equipment that cannot accommodate changing feedstock, evolving safety requirements, or rising energy expectations may become a liability rather than a productivity asset. Likewise, companies that underestimate documentation, sanitation complexity, or regional certification differences may face delayed launches and procurement friction. The upside belongs to operators and suppliers who treat drying as a flexible, compliance-ready process layer rather than a fixed hardware purchase.
Strategic Actions for Decision Makers
For Equipment Manufacturers and Process Suppliers
Position drying systems as integrated process solutions rather than standalone thermal units. Emphasize sanitation efficiency, changeover adaptability, and control precision in product roadmaps, and align development with regulatory expectations that shape buyer purchasing criteria. Where possible, support customers with documentation, commissioning guidance, and service models that reduce validation and maintenance friction. Differentiation will increasingly come from how easily a system fits into multi-product operations and how confidently it supports safety and quality compliance.
- Prioritize modular architectures that allow airflow, capacity, and sanitation configurations to be tuned for different feedstock and facility profiles.
- Strengthen service, training, and compliance documentation as core revenue and retention enablers, not ancillary support functions.
- Track eco-design and safety mandates early so product updates can anticipate procurement requirements rather than react to them.
For Investors and Growth-Focused Buyers
Evaluate the drying sector with a focus on application adjacencies, regional demand formation, and total-cost economics rather than headline capacity alone. Capital and acquisition opportunities are likely to emerge where companies can combine drying technology with integration capabilities, service reach, or niche application expertise. In parallel, watch for supplier consolidation in industrial segments and growth in agile commercial-scale capacity, as both pathways can reshape competitive dynamics.
- Assess target companies on process integration depth, compliance readiness, and the ability to serve multiple drying segments, not solely on equipment specs.
- Factor operating cost dynamics into valuation logic, including sanitation cycle time, energy intensity, and serviceability across mixed production schedules.
- Monitor regional capacity shifts that may change where drying assets are most valuable in the supply chain.
For Procurement Teams and End-Use Operators
Standardize drying procurement around repeatability, sanitation practicality, and compliance documentation. When evaluating options, compare total operating impact rather than purchase price: consider changeover speed, moisture consistency, cleaning compatibility, and how well the system aligns with safety requirements for the specific products being processed. Where production is multi-product or export-oriented, favor configurations that simplify audit readiness and reduce rework risk.
- Define drying specifications by product safety and quality requirements first, then map equipment features to those outcomes.
- Include sanitation, documentation, and energy performance in request-for-quote criteria to avoid hidden operational costs.
- Build flexibility into capacity planning so drying lines can accommodate seasonal variation, feedstock differences, and new product introductions without major retrofit cycles.
Closing Perspective
The food dryer market is moving through a transition in which drying technology is becoming more central to product quality, regulatory readiness, and operational resilience. Growth is being driven by a combination of process innovation, compliance expectations, expanding demand across industrial and commercial segments, and a broader revaluation of equipment around total cost and integration value. The competitive field reflects this shift: leadership is increasingly defined by application fit, hygiene performance, flexibility, and the ability to support buyers through complex compliance and operating environments.
For organizations deciding how to position themselves, the strategic question is less about whether drying capacity is needed and more about which drying archetype matches the product mix, safety requirements, and growth path at hand. Detailed segmentation, regional nuances, and company-level benchmarking can materially improve capital and sourcing decisions, especially where multiple drying technologies, certification pathways, and application profiles intersect. For those seeking a deeper look at those variables, the full research report provides expanded segmentation detail, competitive benchmarking, and tailored decision support beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: Food Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Coconut Milk Powder Market: Why 9.94% CAGR Redefines Global Growth by 2032
By pmarketresearch, 2026-09-21
Coconut Milk Powder Market: Strategic Trends and Commercial Opportunities Through 2032
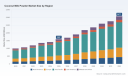
The coconut milk powder market has entered a phase of accelerated, structural growth. Over the historical period from 2020 to 2025, the market expanded from approximately USD 1.0 billion to USD 1.597 billion, reflecting a compound annual growth rate that signals durable demand rather than a temporary spike. During the forecast window from 2026 to 2032, the trajectory continues upward, with projected revenue reaching roughly USD 3.077 billion by the end of the period and a five-year CAGR of 9.94%. These figures place coconut milk powder among the more compelling ingredient categories in the broader plant-based and alternative dairy landscape. The growth is not evenly distributed across regions or applications, but the aggregate momentum is clear: manufacturers, investors, and procurement teams are facing a market that is scaling faster than legacy dairy substitutes in several consumer segments.
Behind the headline numbers lies a market that is still maturing in terms of supply discipline, quality standardization, and regulatory alignment. The concentration metrics underscore this reality: the top three players account for 44.5% of market revenue, while the top five hold 59.0%. This level of concentration indicates a competitive field where scale advantages matter, yet substantial room remains for regional specialists, niche organic suppliers, and vertically integrated processors to capture value. The market is large enough to support diversified strategies but fragmented enough that positioning, technology, and supply chain resilience now determine who wins margin rather than who simply participates.
1. Market Landscape and Core Challenges
A Market Growing on Two Parallel Tracks
The overall expansion reflects a dual dynamic. On one side, full-fat coconut milk powder continues to anchor demand in applications that prioritize richness, mouthfeel, and traditional flavor profiles. On the other, low-fat variants are gaining traction where formulation flexibility, calorie management, and downstream processing compatibility matter more than absolute fat content. The two segments are approaching comparable scale, which tells a story of diversification rather than reliance on a single product architecture. Beverage formulators, bakery developers, and savory sauce manufacturers are selectively choosing between these variants based on functional requirements, not just cost.
Geographically, Asia Pacific carries the largest absolute share of revenue, consistent with the region's production base, domestic consumption habits, and growing export-oriented processing capacity. Europe and North America follow as significant demand centers, driven by premiumization, clean-label expectations, and the ongoing shift toward plant-based alternatives in food service and retail. Latin America and the Middle East/Africa regions contribute meaningful volume, though from smaller bases, and their growth paths are increasingly influenced by cross-border supply arrangements and food safety compliance rather than domestic consumption alone.
Cheese Powder Market
Three Challenges Defining the Market's Next Chapter
First, raw material cost volatility is no longer a cyclical nuisance; it is a structural factor shaping pricing, contracts, and margin planning. Coconut feedstock prices have shown sensitivity to weather patterns, crop cycles, and regional supply tightness. In early 2026, coconut milk powder pricing rose by 3–4% as underlying coconut material costs increased, and earlier data points to ongoing volatility affecting production economics for processors. For manufacturers, this translates into the need for stronger hedging, forward contracting, and formulation strategies that can absorb input swings without eroding competitiveness. For buyers, it means shorter-term price stability can no longer be assumed, and dual-sourcing or specification flexibility may become part of routine procurement design.
Second, regulatory and labeling requirements are intensifying in the most profitable end markets. Food safety authorities in Europe and North America have reinforced labeling rules for powdered foods, including coconut milk powder, with clearer expectations around ingredient declarations, allergen handling, and packaging information. At the same time, government push toward sustainable packaging and plastic reduction is reshaping packaging roadmaps across food categories. Import requirements add another layer of complexity, with phytosanitary certificates and market-specific entry conditions becoming standard for coconut milk powder shipments. The practical effect is a rising compliance bar that rewards companies with disciplined documentation, traceable supply chains, and packaging strategies already aligned with destination-market expectations.
Third, the market is reaching an inflection point where consistency and functionality increasingly separate premium suppliers from commoditized participants. Spray-drying efficiency, particle uniformity, reconstitution behavior, and flavor stability are becoming differentiators rather than table stakes. As applications expand into beverages, bakery, confectionery, soups, sauces, and other formats, the ingredient must perform reliably across different processing environments. Companies that can deliver consistent technical performance while managing cost and compliance are better positioned to move up the value chain, whereas suppliers competing primarily on price face increasing pressure as specifications tighten and audits become more frequent.
2. Key Drivers Shaping Market Trajectory
Technology and Processing Innovation
Processing technology is a primary enabler of the market's next wave of growth. Advanced spray-drying and integrated processing investments are improving powder consistency, yield, and functional reliability. In April 2026, Thai Coconut Public Company Limited increased investment in advanced spray-drying and processing technologies aimed at improving coconut milk powder efficiency and consistency, a move that reflects a broader industry focus on turning production capability into a strategic advantage. Around the same time, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. These developments matter because they do not simply increase capacity; they improve the economics of premium-grade output and reduce variability across batches, which is critical for industrial buyers who depend on repeatable formulation performance.
For the broader market, the technological trajectory points toward more tightly controlled particle characteristics, improved solubility profiles, and greater ability to tailor fat content without sacrificing sensory qualities. These improvements widen the range of applications where coconut milk powder can substitute or complement other ingredients, especially in plant-based dairy alternatives, ready-to-drink beverages, and formulated foods that require stable powders with predictable behavior during storage and reconstitution.
Consumer Demand and Corporate Procurement Behavior
Demand-side change is being driven by the continued expansion of plant-based eating, but also by more specific shifts in how food manufacturers and food service operators select ingredients. Coconut milk powder benefits from its positioning as a recognizable, consumer-friendly plant-based ingredient with a strong flavor association and broad acceptability. At the same time, corporate buyers are increasingly balancing functionality with clean-label expectations, sourcing transparency, and sustainability credentials. This creates a layered demand environment: one layer is volume-driven and price-sensitive, while another layer rewards suppliers who can document origin, processing standards, and packaging responsibility.
Worldwide Coconut Oil Fat Powder Market
The application spread reinforces this dynamic. Beverages remain a major demand node, but bakery, confectionery, soups, sauces, and other categories are not merely secondary users; they represent formulation problems that coconut milk powder can solve when the right fat level, solubility, and flavor profile are available. Suppliers that understand application-specific requirements are better able to move beyond commodity positioning and into partnership-based selling, where technical support and customization become part of the value proposition.
Supply Chain Realignment and Cost Structure Pressures
The supply chain for coconut milk powder is being reshaped by a combination of input volatility, export documentation requirements, and the search for more predictable sourcing. Raw coconut material price volatility has repeatedly affected production costs, which pushes manufacturers to strengthen relationships with growers, consider regional diversification, and improve inventory planning. Import requirements, including phytosanitary certificates and market-specific food import rules, add time and cost to cross-border transactions, especially for suppliers serving regulated markets in Europe and North America.
This environment favors companies with integrated operations, where control over processing reduces exposure to intermediaries and improves quality oversight. It also favors exporters who invest early in compliance readiness and documentation fluency, because these capabilities lower friction at border points and shorten time to market. For buyers, the practical takeaway is that supply resilience is increasingly a procurement criterion alongside price and quality, especially for manufacturers who cannot afford production interruptions or specification failures.
PW Consulting Health Care Research Center
Regulatory and Sustainability Pressures as Market Filters
Regulatory and sustainability expectations are increasingly acting as market filters rather than mere compliance tasks. Labeling mandates for powdered foods, sustainable packaging guidance, and plastic reduction targets are reshaping product design decisions. These requirements are not uniform across regions, which means that suppliers serving multiple markets must manage a patchwork of rules, but they also create advantages for companies that have already modernized packaging formats, documentation systems, and labeling processes. In effect, the regulatory environment is raising the cost of entry for poorly organized players while rewarding those with established quality and compliance infrastructure.
This dynamic is particularly relevant for premium and organic segments, where buyers expect both ingredient integrity and responsible packaging. Companies that can align product claims with verifiable practices are more likely to secure long-term contracts with brands that face their own consumer and retailer scrutiny.
3. Competitive Landscape and Leading Strategies
Differentiation Through Integration, Technology, and Positioning
The competitive set reflects a range of strategic models. Axelum Resources Corp. operates as a fully integrated manufacturer and exporter of premium coconut products, including coconut milk powder for global food and beverage brands, with a focus on export-oriented value-added production. Thai Coconut Public Company Limited stands out as a leading manufacturer with advanced spray-drying technology, an asset that supports consistency and scale in coconut milk and coconut milk powder production. Red V Foods serves North American food manufacturers, food service, and private label customers with premium coconut products, positioning itself within a mature demand center where specification and service reliability often matter as much as price.
Bata Food operates as an international supplier of organic and conventional coconut milk powder with offices in the Netherlands and the USA, a footprint that supports access to regulated Western markets and suggests a strategy built on trade connectivity and product range breadth. In the plant-based and dairy-alternative segment, Royal Grove Foods has launched plant-based coconut milk ranges for food manufacturing and home use, signaling movement toward end-use positioning rather than ingredient-only distribution. Jaindi Export Pvt. Ltd. and Omilco Exports represent Sri Lankan exporters with organic and premium organic coconut solutions respectively, both active in international food exhibitions and oriented toward export channels. Coco Factory Pvt. Ltd. emphasizes vegan coconut milk powder crafted from real coconut milk for plant-based dairy alternatives, an explicit product Narrative that aligns with consumer-facing positioning.
These profiles illustrate a market where leadership is being built through different paths: vertical integration, technology investment, organic certification, application-specific product narratives, and trade-network access. Few players are competing on a single dimension; instead, the stronger positions combine processing capability, market access, and a clear value proposition tied to either premium quality, organic integrity, or application performance.
Recent Moves That Signal Strategic Direction
The most recent industry activity reinforces the emphasis on capability, visibility, and market access. In April 2026, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. Thai Coconut Public Company Limited increased investments in advanced spray-drying and processing technologies for improved efficiency and consistency. In May 2026, Omilco Exports appeared as a first-time exhibitor at Fine Food Australia, showcasing premium organic coconut milk powder, cream, and related products. Jaindi Export Pvt. Ltd. exhibited organic coconut milk powder at Gulfood 2026. These actions collectively indicate that companies are pursuing growth through both operational upgrades and direct market engagement, using trade platforms to reach buyers in high-value regions and using technology and integration to defend margin and quality.
How the Competitive Structure Is Evolving
The market is likely to continue evolving along three lines. Integration will deepen where scale and cost control matter most, especially among exporters serving regulated markets that demand consistency and documentation. Differentiation will intensify among organic, premium, and application-focused players who can justify higher price points through verified quality, technical support, and packaging compliance. At the same time, new entrants and regional specialists can still find openings if they focus on underserved applications, specific geographic routes, or certified organic supply that larger players do not fully address. The moderate concentration in the market means consolidation is possible over time, but it is not yet a foregone conclusion; the more immediate trend is a widening gap between suppliers with integrated, technology-enabled operations and those competing primarily on loose specifications and price.
4. Outlook: Three Trends Shaping the Next Three to Five Years
Premiumization and Functional Tailoring Will Drive Higher-Value Volume
As the market expands from roughly USD 1.7 billion in 2026 toward more than USD 3.0 billion by 2032, volume growth alone will not explain the gain. A meaningful portion of future growth will come from higher-value usage where coconut milk powder is selected for specific sensory and functional outcomes. Formulators will continue to differentiate between full-fat and low-fat options based on application needs, and suppliers that offer tailored specifications, reliable reconstitution, and stable flavor will capture more of the margin pool. This trend favors manufacturers that can support buyers with technical expertise and consistent batches, and it raises the stakes for commoditized suppliers whose products are easiest to replace.
Compliance and Packaging as Competitive Advantage
Over the next few years, regulatory expectations around labeling, food safety, and sustainable packaging are likely to become more embedded in procurement decisions rather than treated as separate compliance workstreams. Suppliers that align product design with destination-market rules and demonstrate credible packaging roadmaps will gain an edge in Europe, North America, and other regulated channels. Conversely, companies that lag on documentation, traceability, or packaging transition may find themselves constrained to less demanding channels, where price competition is more intense and brand visibility is lower. In this environment, compliance becomes a market-access tool as much as a legal obligation.
Regional Rebalancing and Export Route Optimization
The market's center of gravity will remain Asia Pacific-dominant in volume terms, but growth in demand from Europe, North America, and selected emerging regions will encourage more deliberate route-to-market planning. Recent exhibition activity in Australia and the Middle East, combined with ongoing investments in processing capability, suggests that suppliers are actively testing and strengthening distribution pathways beyond traditional channels. Over the forecast period, expect more emphasis on export readiness, phytosanitary and import compliance, and localized customer support. This rebalancing creates opportunities for intermediaries, specialized traders, and processors that can bridge production clusters with end-market requirements efficiently.
Risks and Uncertainties to Monitor
Several factors could alter the trajectory. Continued raw material price volatility may compress margins for operators without strong contracting or hedging flexibility. Tightening regulations, especially where labeling, packaging, and import requirements diverge across markets, could raise operating costs and slow product launches. If demand for plant-based alternatives softens in specific categories or price-sensitive segments, coconut milk powder could face sharper competition from other plant-based fats and powders. Finally, weather-related disruptions and crop variability in key producing regions could affect both supply reliability and pricing stability, making multi-region sourcing and inventory planning more important than ever.
5. Strategic Implications for Decision-Makers
For Manufacturers
Prioritize processing consistency and application-specific value over volume alone. Investments in spray-drying efficiency, quality control, and integrated processing are becoming decisive because they directly influence batch reliability, specification control, and the ability to serve demanding industrial buyers. At the same time, build compliance infrastructure early, including labeling readiness, documentation fluency, and packaging transitions, so that new market entry does not become a bottleneck. Where raw material exposure is significant, strengthen supplier relationships and consider forward arrangements that reduce vulnerability to price swings.
For Investors
Look for operators that combine credible technology or integration with clear market access and documentation capability. In a market where the top players already hold meaningful share but concentration is not absolute, value creation is likely to accrue to companies that can defend premium positioning, manage volatility, and expand into regulated channels with lower friction. Pay close attention to how suppliers are handling compliance, packaging, and organic or premium differentiation, because those factors increasingly determine customer stickiness and pricing power.
For Procurement and Sourcing Teams
Treat resilience as a core sourcing criterion. Dual sourcing, specification flexibility, and supplier qualification based on consistency and compliance can reduce exposure to both price volatility and supply interruption. When evaluating suppliers, assess not only price and basic quality but also documentation maturity, packaging alignment with destination-market expectations, and the ability to support application needs. Shorter-term price advantages can be outweighed by higher total cost if a supplier cannot meet audit, labeling, or reliability requirements.
Why Timing and Granularity Matter Now
The market is large enough to reward strategic commitment and fast enough that timing matters. With the forecast period extending through 2032 and a CAGR in the high single digits, decisions made now about product specifications, sourcing routes, compliance readiness, and application targeting will shape competitiveness for years. Companies that act on broad trends alone may capture some growth, but those that combine trend awareness with detailed segmentation insight, regional compliance nuance, and application-specific formulation considerations are more likely to secure durable advantage. For teams seeking to move from general market awareness to targeted operating decisions, more granular data on regional and application dynamics, competitive positioning, and scenario planning can materially improve the quality of strategy and execution.
For detailed analysis of this topic, please visit the official page: Coconut Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Offset Printing Plate Market: How Asia Pacific's 79M Share Reshapes Long-Term Outlook
By pmarketresearch, 2026-09-21
Digital Offset Printing Plate Market: Strategic Trends & Commercial Opportunities Beyond 2025
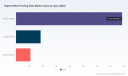
The digital offset printing plate market stands at a critical inflection point, shaped by the intersection of sustainability mandates, material science breakthroughs, and shifting print volumes across commercial and packaging applications. Described by a base-year valuation of USD 216.1 million in 2025 with a compound annual growth rate of 2.35 percent projected through 2032, the market reflects a measured but sustained expansion trajectory. Historical progression from 2020 to 2025 reveals a modest recovery from pandemic-era disruptions before stabilizing into a period of incremental growth. Forward-looking projections show volatility across near-term years, including a slight contraction in 2028 before resuming upward momentum, signaling a landscape defined less by linear growth and more by periodic realignment as pricing pressures, regulatory execution, and substrate innovation reshape buyer priorities.
For executives, investors, and procurement leaders, the narrative is no longer about market size alone. The strategic question centers on where value is being created as the industry transitions toward chemistry-free workflows, waterless imaging alternatives, and integrated final-exposure systems. This analysis maps the structural forces driving change, the competitive positioning of incumbents and specialists, and the actionable implications for stakeholders navigating the next cycle of investment, sourcing, and product strategy.
Market Context & Core Challenges
The current market is characterized by technological maturation rather than breakthrough expansion. The steady pace of growth masks underlying complexity: while aluminum-based formats continue to anchor production value due to their durability and consistent run-length performance, the broader ecosystem is being recalibrated by environmental compliance costs, substrate diversification, and operational efficiency demands. Prices are under pressure from raw material volatility, while demand patterns shift as packaging converters prioritize flexible, high-speed workflows and commercial printers consolidate around shorter-run, high-quality output models. The competitive environment reflects moderate concentration, with a small group of established players and emerging specialists carving out defensible niches. This structure rewards firms that can translate innovation into workflow integration and regulatory readiness.
Three challenges dominate the near-term agenda. First, regulatory tightening is reshaping the cost and compliance architecture of plate manufacturing and imposition. Standards governing chemical exposure, solvent handling, and waste management have moved from peripheral considerations to core operational requirements, forcing suppliers to redesign formulations and production protocols. Second, substrate performance trade-offs remain a persistent friction point. While aluminum continues to deliver superior print consistency for demanding packaging runs, alternative substrates face ongoing questions around scratch resistance, dimensional stability, and compatibility with advanced curing chemistries, constraining adoption in high-value applications. Third, the market is experiencing demand fragmentation across segments. Packaging continues to absorb a significant share of output, but commercial printing and periodical applications are subject to rapid volume swings as digital alternatives and on-demand models compress traditional run lengths. These dynamics require suppliers and buyers alike to align capacity, product mix, and service models with more volatile demand signals.
Key Drivers of Market Evolution
Technology Innovation And Imaging Breakthroughs
Advancements in thermal and photopolymer imaging are redefining performance expectations for digital offset plates. Next-generation thermal formats are delivering sharper image transfer, improved chemical resistance, and better handling of variable exposure environments, enabling printers to reduce scrap rates and maintain quality across mixed-material jobs. In parallel, improvements in photopolymer structures and violet imaging chemistries are extending run lengths and improving cure compatibility, particularly for UV-enabled packaging and label work. These technical gains are being reinforced by process-free and chemistry-free formulations that remove the need for wet-processing steps, simplifying pressroom operations while reducing consumable waste and operator exposure. The strategic implication is clear: plate performance is increasingly judged not only by output quality but by total workflow efficiency, including setup time, processing complexity, and compatibility with integrated imaging systems.
PW Consulting
Regulatory And Compliance Pressures
Environmental and safety regulations are no longer passive constraints; they are active design parameters. Frameworks governing chemical substances have compelled manufacturers to reduce hazardous emissions, minimize waste streams, and formalize material handling procedures throughout the production lifecycle. Compliance has become a competitive differentiator for suppliers that can demonstrate process-free operation, lower chemical footprints, and documented waste management practices. In parallel, occupational safety expectations around photopolymer handling and solvent use have raised the bar for supplier-support programs, technical documentation, and pressroom training. These shifts are accelerating market acceptance of greener plate technologies, with eco-label certifications and sustainability criteria increasingly influencing procurement decisions across regional and multinational print operations.
Flexographic Printing Plate Market
Demand-Side Shifts In Consumer And Enterprise Behavior
Demand structures are being reshaped by the rise of shorter production runs, personalized packaging, and brand-driven print differentiation. Packaging converters and commercial printers alike are seeking plates that support rapid job changes, strong scratch resistance, and consistent performance across diverse substrates and ink systems. As brands invest more in tactile packaging finishes, label sophistication, and limited-edition runs, the need for plates that can balance speed with image fidelity is intensifying. At the same time, digital substitution continues to pressure longer-run commercial volumes, pushing print service providers to compete on flexibility and quality rather than volume alone. This environment favors plate technologies that enable faster setup, lower chemistry dependency, and reliable performance on demanding runs, while also rewarding suppliers that can help customers reduce waste and operational cost per impression.
Supply Chain And Cost Structure Dynamics
Cost pressure remains a persistent force, amplified by aluminum volatility, processing chemistry inputs, and the operational expense of compliance. Suppliers are responding through formulation optimization, streamlined processing requirements, and greater emphasis on durability to reduce total cost of ownership. Buyers are increasingly weighing lifecycle economics over unit price, considering factors such as scratch resistance, handling robustness, and consumable savings from process-free designs. The net effect is a shift toward value-based evaluation, where performance consistency and workflow integration can offset raw material fluctuations. This dynamic also encourages consolidation of supplier relationships and technical support, as customers look for partners that can standardize product performance across locations and reduce the complexity of maintaining multiple plate formats.
Competitive Landscape And Strategic Positioning
The competitive environment is defined by a mix of large-incumbent capabilities and specialized technical differentiation. Several established players have focused on thermal digital offset plates for commercial and packaging work, emphasizing image sharpness, chemical resistance, and compatibility with next-generation imaging systems. Others have built strong positions in process-free and chemistry-free formats, leveraging proprietary technologies to reduce wet-processing needs and improve scratch resistance. A third group has pursued waterless and eco-friendly plate architectures aimed at lowering chemical use and environmental impact in offset workflows, particularly for packaging. Some suppliers are extending beyond plate materials into integrated imaging and press solutions, creating tighter coupling between plate format and on-press imaging workflows. Across the field, differentiation is increasingly tied to durability, workflow compatibility, regulatory readiness, and the ability to reduce total processing cost.
Recent developments illustrate how these firms are executing against the market's structural forces. In early 2025, one major supplier introduced a next-generation thermal digital offset plate designed to improve image sharpness and chemical resistance for commercial and packaging applications, aligning with the broader push toward sharper transfer and more robust handling. Later in 2024, another leading manufacturer launched an advanced photopolymer plate with improved durability and stronger compatibility with UV-curable inks, addressing the growing demand for high-performance packaging and label workflows. Third, a strategic partnership announced in mid-2024 between a plate specialist and a global printing equipment manufacturer signaled a move toward co-developed integrated plate and imaging systems, aiming to streamline offset workflows and reduce integration friction. Finally, an eco-focused brand introduced a process-free plate with enhanced contrast, scratch resistance, and cost savings for commercial printing, reinforcing the trend toward chemistry-free formats that lower operational complexity.
These moves reflect broader competitive patterns. Incumbents are strengthening technical performance while embedding sustainability into product definitions, using process-free chemistries and waterless options to address regulatory and cost pressures. Specialists are competing on differentiation, targeting packaging durability, label compatibility, and reduced chemical exposure. The rise of integrated system partnerships suggests a shift toward ecosystem-based value creation, where plate performance is judged alongside press readiness, imaging stability, and total workflow efficiency. Market evolution is likely to continue along two parallel paths: consolidation among players seeking scale and broad format coverage, and continued fragmentation among firms pursuing deep specialization in high-value applications or sustainable processing.
Worldwide Printing Plate Market
Future Trends And Commercial Opportunities (2026–2032)
The market's trajectory over the next several years will likely be shaped by three overlapping trends.
Sustained adoption of process-free and low-chemistry plate formats. As regulatory expectations solidify and pressroom cost pressures persist, demand is expected to tilt further toward plates that eliminate or reduce wet-processing steps. The commercial opportunity lies in building supply capability around durable, scratch-resistant, chemistry-light formats that reduce consumables, simplify operator procedures, and lower exposure risk. Suppliers that can pair these formats with strong technical support and workflow documentation will be better positioned to capture value in regulated and cost-sensitive environments.
Integration of plate and imaging systems for workflow efficiency. The push toward seamless offset workflows is likely to intensify as printers seek to reduce setup variability and improve run consistency. Opportunities are emerging for companies that can co-design plate specifications with imaging systems, standardize exposure protocols, and reduce compatibility risks across equipment fleets. This trend rewards partnerships, modular product architectures, and service models that address the entire imaging chain rather than isolated consumables.
Substrate diversification and packaging-specific performance gains. While aluminum substrates remain central, the market is likely to see continued experimentation with alternative formats where durability, dimensional stability, and ink compatibility can be proven at scale. The commercial opportunity is concentrated in packaging and label applications where run quality, scratch resistance, and chemistry compatibility directly influence conversion efficiency and customer acceptance. Firms that can deliver packaging-grade performance with reduced environmental footprint will have a clearer path to premium positioning.
These trends carry uncertainty. Pricing volatility in raw materials may compress margins if cost savings from process-free designs are not fully realized in the field. Demand fragmentation across commercial and periodical segments may create overcapacity risk if volume assumptions are misaligned with actual run-length trends. Regulatory interpretations can also diverge across regions, creating uneven compliance costs and slowing adoption of certain formulations. Stakeholders should treat these variables as design constraints for capacity planning, product mix, and supplier selection rather than static assumptions.
Actionable Recommendations For Decision Makers
For manufacturers and plate suppliers: Prioritize process-free and chemistry-light development as a core product strategy rather than a marginal offering, and pair formulation advances with measurable claims around scratch resistance, handling durability, and total processing cost. Invest in integration readiness by aligning plate specifications with imaging and press workflows, and build technical support programs that help customers standardize performance across sites. Track regulatory developments closely and treat compliance capability as a market-entry requirement, especially where chemical handling and waste management expectations are tightening.
For investors: Focus on value creation potential rather than raw volume growth. Evaluate companies by their ability to deliver workflow-integrated solutions, sustainable-processing formats, and packaging-grade performance with defensible cost profiles. Watch for partnership activity that signals ecosystem expansion, as integrated plate-and-imaging playbooks may create stronger customer lock-in and margin resilience. In parallel, assess exposure to raw-material volatility and the degree to which cost savings are embedded in total cost of ownership claims rather than unit pricing alone.
For procurement teams and print service providers: Shift sourcing decisions toward total workflow economics, including processing complexity, consumable usage, setup efficiency, and damage resistance under handling and production stress. Prioritize formats that reduce chemistry dependency where feasible, and request documented performance consistency across multiple run lengths and substrate conditions. Where feasible, consolidate supplier relationships around formats that standardize exposure protocols and simplify pressroom training, reducing operational friction while maintaining quality standards.
For stakeholders seeking a more detailed view of segment dynamics, regional demand structures, competitive share breakdowns, and pricing scenarios across the forecast horizon, a full market study can provide the granular benchmarks required for product planning, investment modeling, and sourcing decisions. The broader market signals are clear: the digital offset printing plate landscape is shifting from volume-based growth toward performance, sustainability, and workflow integration. Organizations that act on these signals with clear product and sourcing strategies will be better positioned to capture durable value in the years ahead.
For detailed analysis of this topic, please visit the official page: Digital Offset Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Thermostats Market 2026: Beyond the 15.05% CAGR Growth Trajectory
By pmarketresearch, 2026-09-21
The Smart Thermostats Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global smart thermostats market has transitioned from a niche convenience segment to a foundational component of connected home and building energy management. Valued at approximately $4.94 billion in 2025, the market has expanded from $2.21 billion in 2020, reflecting a compound annual growth rate of 15.05% projected through 2032, when revenues are expected to reach $13.18 billion. This trajectory signals more than consumer interest; it reflects a structural shift in how heating, ventilation, and air conditioning systems are optimized, monitored, and integrated into broader energy ecosystems. For executives, investors, and procurement leaders, the window to shape positioning is narrowing as connectivity standards, regulatory frameworks, and AI capabilities accelerate simultaneously.
Market Snapshot and Structural Shifts
The revenue path from 2020 through 2032 illustrates a market gaining momentum rather than merely recovering from earlier volatility. Growth accelerated notably around 2024–2025, with the base year marking a step change in adoption intensity across residential and commercial environments. The forecast period to 2032 suggests continued expansion, though the pace will increasingly hinge on how quickly interoperability, installation friction, and data governance concerns are resolved. Market concentration remains moderately fragmented at the top, with the three largest players holding roughly 37.5% of share and the top five accounting for about 48.0%. This distribution leaves meaningful room for regional specialists, ecosystem-driven entrants, and companies that can narrow the gap between premium intelligence features and accessible price points.
Several structural tensions define the current environment. First, the market is navigating a shift from standalone device sales toward integrated service and software value, where recurring energy savings, predictive maintenance, and ecosystem lock-in begin to matter as much as hardware margins. Second, installation complexity and legacy HVAC compatibility continue to create friction in broader residential rollouts, pushing manufacturers to design for retrofit ease without sacrificing performance. Third, differing regional approaches to connectivity oversight and energy efficiency standards are shaping product roadmaps unevenly, requiring companies to balance unified global platforms with localized compliance and pricing strategies. These dynamics create both risk and differentiation potential for players that act early.
Core Drivers Reshaping Demand and Competition
Technology Innovation and the Move Toward Predictive Control
The most durable driver is the maturation of AI-enhanced learning, occupancy sensing, and adaptive scheduling. Devices are no longer limited to remote control via mobile applications; they are increasingly capable of recognizing usage patterns, adjusting to weather forecasts, and coordinating with ventilation or air quality sensors. Recent product introductions reflect this shift toward intelligence that is both more responsive and more accessible. In January 2025, ecobee launched the Smart Thermostat Essential at CES 2025, offering adaptive learning and mobile app control at a more accessible price point, signaling that predictive features are being brought down-market rather than reserved for premium tiers. A few months later, Alarm.com introduced the ADC-T25 Smart Thermostat, emphasizing cost-efficiency, advanced HVAC control, and simplified installation for broader residential adoption. These launches illustrate a dual strategy: expand the installed base through easier deployment while retaining differentiated algorithms that improve comfort and efficiency over time.
Policy and Regulatory Environments as Demand Catalysts
Policy momentum continues to shape purchasing behavior, particularly where energy efficiency mandates, incentive programs, and certification labels lower the effective cost of adoption. ENERGY STAR certification and Matter compatibility have become practical signals for both consumers and commercial specifiers, reducing uncertainty around interoperability and verified savings. At the same time, the broader connectivity environment is not uniform. In January 2025, the U.S. Court of Appeals for the Sixth Circuit struck down the FCC’s 2024 Open Internet Order, reclassifying broadband as an information service and ending federal net neutrality oversight. Several states, including California, Washington, Oregon, and Vermont, have maintained statewide net neutrality requirements that restrict ISP blocking, throttling, or prioritization of broadband traffic. The ruling also left Congress as the primary pathway for new federal legislation on broadband access. For smart thermostat providers, the practical implication is that residential and commercial connectivity assumptions cannot be taken for granted; product architectures must remain resilient across varying ISP practices, and go-to-market strategies may need to account for regional differences in network treatment and reliability expectations.
Demand-Side Behavior and Building Operations Priorities
On the demand side, residential buyers increasingly view smart thermostats as part of a wider smart home investment tied to comfort, air quality, and energy cost management. In commercial and industrial settings, the emphasis shifts toward integration with building automation systems, occupancy-based scheduling, and centralized control across multiple zones. Recent product activity underscores this bifurcation. In March 2026, Carrier launched the Smart Thermostat Advanced and enhanced Smart Thermostat models with InteliSense technology and a ComfortAdjust feature tailored for Performance Series heat pumps, reinforcing the value of system-specific optimization in higher-end residential and light commercial applications. Meanwhile, companies focused on hospitality and multi-site building environments have continued to emphasize no-door-interface designs and occupancy-based control to reduce manual adjustments and standardize environmental performance across properties. The commercial segment’s growth is increasingly tied to operational outcomes—fewer service calls, more consistent zone control, and better alignment between HVAC runtime and actual occupancy—rather than device novelty alone.
Supply Chain and Connectivity Cost Structures
Behind the product conversation, connectivity remains a structural cost factor. Broadband infrastructure represents the primary ongoing cost for smart thermostat data connectivity and cloud services, which means that subscription pricing, data handling architecture, and device-side processing design directly influence long-term margin profiles. Manufacturers that can reduce dependency on continuous heavy cloud processing—through smarter edge logic or more efficient scheduling algorithms—may gain flexibility in pricing and resilience against connectivity cost pressure. At the same time, component availability, platform certification cycles, and the cost of maintaining broad HVAC compatibility all shape time-to-market and portfolio breadth. The companies that manage these inputs well are increasingly those that treat connectivity not as an afterthought but as a core design constraint, balancing feature richness with sustainable service economics.
WiFi Thermostats Market
Competitive Positioning and the Evolution of the Market Map
The competitive field blends established home automation names, traditional HVAC and building technology players, and specialist firms with deep application focus. Google LLC continues to emphasize AI-driven learning and voice control through the Nest Learning Thermostat (4th generation), aligning residential smart thermostat adoption with wider smart home integration. ecobee Inc. has built its positioning around air quality sensing, predictive learning, and broad ecosystem compatibility, with its Essential launch reinforcing a tiered approach that spans premium and value-conscious buyers. Honeywell International Inc. has leaned into Matter compatibility, dual-band connectivity, and ENERGY STAR certification across its T9, X8S, and X2S Wi-Fi Smart Thermostats, highlighting standards alignment as a trust signal. Amazon.com, Inc. offers an app-based and voice-integrated thermostat developed in partnership with Resideo Technologies, leveraging distribution and voice ecosystem reach rather than attempting to lead on standalone HVAC engineering. Emerson Electric Co. focuses on the Sensi Touch and Sensi series with Alexa integration, touch interfaces, and broad HVAC compatibility, creating a practical middle ground between advanced features and installation flexibility.
In the commercial and industrial direction, Johnson Controls International plc emphasizes building automation system integration, while Carrier Global Corporation pursues system-specific optimization through InteliSense technology and humidity control in its Infinity System Control and Smart Thermostat portfolio. Schneider Electric SE extends connected home solutions through IoT platform integration, and Resideo Technologies, Inc. continues to develop Honeywell Home-branded models such as the X2S and X8S with advanced AI and smart home features; its January 2025 introduction of the Honeywell Home X2S at CES 2025, featuring Matter compatibility and ENERGY STAR certification, reflects the same interoperability emphasis seen across the broader field. Specialist entrants add application depth: Tado GmbH focuses on occupancy sensing and precise heating and cooling optimization with its V3+ and Sense devices, while Verdant Solutions LLC, operating under Copeland, targets commercial hotel and building applications with VX and VX4 thermostats designed around no-door-interface interaction and occupancy-based control.
The landscape is evolving along three overlapping vectors. First, interoperability and standards alignment are becoming table stakes, with Matter compatibility and ENERGY STAR certification increasingly expected rather than optional differentiators. Second, there is a subtle fragmentation between broad-platform players and application specialists, with the latter competing on installation simplicity, zone-specific control, and vertical workflow fit rather than general feature count. Third, the market is seeing consolidation pressure at the edges, where device-only businesses may struggle to defend margins unless they attach software value, service relationships, or integration partnerships. Companies that can combine credible HVAC compatibility, standards-aligned connectivity, and clear operational benefits are best positioned to expand share without relying solely on price competition.
Forward Outlook: Three Trends to Track Through 2032
The next three to five years are likely to be defined by a shift from device adoption to integrated optimization. The first trend is the normalization of predictive and occupancy-aware control as baseline expectations rather than premium extras. As adaptive learning, sensor integration, and weather-responsive scheduling become more common, value will shift toward accuracy, low-friction setup, and measurable energy outcomes. Manufacturers that can demonstrate consistent savings across varied housing types and HVAC configurations will have stronger positioning in both retail and specification channels.
PW Consulting
The second trend is deeper integration with broader building and home ecosystems. Smart thermostats are increasingly evaluated alongside air quality monitors, ventilation controls, voice platforms, and centralized management dashboards. In commercial environments, this points toward more unified building automation interfaces and occupancy-driven scheduling that reduces manual intervention across multiple zones. The commercial opportunity lies not in selling more devices per se, but in enabling operators to manage comfort, runtime, and maintenance more efficiently through a single coordinated layer.
The third trend is regulatory and connectivity-driven fragmentation in market access. With federal net neutrality oversight ended in January 2025 and several states maintaining their own rules, broadband treatment is no longer uniform, and Congress remains the only clear path for new federal legislation. Combined with the fact that broadband infrastructure underpins the ongoing cost of data connectivity and cloud services, this environment favors designs and business models that can tolerate variability in network conditions and that do not depend on a single connectivity assumption. Companies should anticipate that product roadmaps, pricing structures, and service commitments may need to be adapted regionally rather than deployed identically across all markets.
These trends create opportunity, but also uncertainty. Adoption may be moderated where installation complexity remains high, where older HVAC systems limit feature compatibility, or where consumers and building operators are slow to trust algorithmic control without clear proof of savings. Regulatory shifts, standards evolution, and connectivity cost pressure could also reshape margin expectations over time. The most resilient strategies will be those that treat these uncertainties as design inputs rather than external shocks.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Prioritize interoperability and installation simplicity as simultaneous growth levers. Standards alignment, broad HVAC compatibility, and reduced setup friction expand the addressable base, while differentiated intelligence features protect margin and build loyalty. Consider how much control logic can be handled on-device to manage long-term connectivity and cloud service costs, and structure product tiers so that predictive features are accessible without undermining premium positioning. Where feasible, design for integration with wider home or building automation workflows rather than competing solely on isolated device performance.
Thermostats Market
For Investors and Strategic Capital Allocators
Look for businesses that demonstrate durable value beyond initial hardware sales. Recurring savings verification, software-enabled differentiation, and ecosystem relationships often signal stronger long-term economics than feature parity alone. Pay attention to companies that are expanding into commercial and multi-site applications, where operational outcomes and centralized control can support more predictable demand than purely consumer-driven cycles. Also monitor exposure to connectivity cost structures and regional regulatory variance, since these factors can influence margin stability and market access over the forecast period.
For Procurement and Building Operations Leaders
Evaluate smart thermostats as part of a broader energy and comfort management strategy rather than as standalone replacements. Favor solutions with strong HVAC compatibility, clear standards alignment, and occupancy or air quality features that match your operating profile. In multi-site or commercial environments, prioritize centralized visibility, consistent zone control, and support for occupancy-based scheduling to reduce manual adjustments and simplify maintenance planning. Where possible, request evidence of savings and integration behavior across similar building types to reduce deployment risk.
The smart thermostats market is expanding quickly, but the strategic contest is already moving from adoption volume to integration quality, operational impact, and resilience across connectivity and regulatory conditions. Detailed segmentation data, regional breakdowns, and tailored scenario analysis can help translate these trends into specific product, pricing, and investment decisions. For those seeking a deeper view of subsegments, competitive benchmarks, and actionable recommendations suited to a particular market or application, the full PW Consulting research report provides the supporting detail needed to move from market intelligence to execution.
For detailed analysis of this topic, please visit the official page: Smart Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LED Billboard Market 2026-2032: Why 6.98% CAGR Reshapes Growth Beyond $344.8M
By pmarketresearch, 2026-09-21
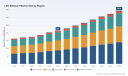
LED Billboard Market: Strategic Trends and Commercial Opportunities in a Maturing Out-of-Home Display Ecosystem
Market Reality and Core Challenges
The LED billboard market has moved from a phase of rapid capacity expansion into a period of more deliberate, value-driven growth. Between 2020 and 2025, the sector advanced from roughly 163 million USD to 215 million USD, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon extending to 2032. By the end of that forecast window, revenue is projected to approach 345 million USD, indicating that the industry is not stalling but recalibrating around more durable demand drivers. The growth trajectory is steady rather than explosive, which means competitive advantage is increasingly defined by deployment quality, integration capability, and operational resilience rather than sheer installation volume.
This maturity brings a set of structural challenges that decision-makers need to address directly. First, the market is experiencing a shift from headline growth to margin discipline. Outdoor LED billboards are capital-intensive assets with long planning cycles, permitting requirements, and site-specific engineering constraints. Revenue growth alone no longer guarantees healthy execution economics. Installations can vary widely in complexity and cost depending on size, resolution, and local conditions, so organizations that do not manage project scoping, site readiness, and component selection carefully can see returns erode even as top-line activity expands.
Second, the industry is navigating a tighter regulatory and compliance environment. Signage rules are becoming more detailed, especially in jurisdictions that are scrutinizing installation practices, labeling, and visual impact for electronic displays. In practical terms, this increases the burden on developers and operators to demonstrate compliance early in the project lifecycle. Companies that treat compliance as an afterthought face delays, redesigns, and reputational risk, while those that build regulatory readiness into their product and deployment processes gain a smoother path to commercialized installations.
Third, supply-side volatility remains a core turning point for the market. High-end components, particularly LED chips and driver ICs, represent a significant share of the bill of materials, and premium versions can carry materially higher input costs. At the same time, trade policy uncertainty around key hardware components can introduce short-notice pricing pressure. Combined with periodic supply chain disruptions affecting specialized parts, this environment rewards firms that have diversified sourcing, strong inventory planning, and enough design flexibility to substitute components without compromising performance.
Key Market Drivers
Technology innovation continues to be one of the most important catalysts in the LED billboard market, but the nature of innovation is changing. The competitive focus is moving beyond brightness alone toward integrated performance: better color calibration, more consistent outdoor visibility across viewing conditions, and smarter content optimization. AI-driven content tools and high-brightness modules are becoming relevant differentiators because they improve the effectiveness of the display once it is installed. For advertisers and operators, this means the value of a billboard increasingly depends on how well the hardware and software work together in live outdoor environments, not just on raw pixel specifications.
Policy and regulatory dynamics are also shaping demand in more nuanced ways than a simple expansion or restriction narrative would suggest. In some regions, updated signage compliance requirements are prompting re-examination of installation practices and product labeling for electronic displays. These requirements can slow individual projects, but they also raise the barrier to lower-quality entrants and encourage standardization around more durable, better-documented systems. For the market overall, this creates a subtle shift in favor of established manufacturers and operators that can prove reliability, traceability, and long-term maintainability.
Demand-side behavior is supporting this shift. Advertisers and venue operators are looking for outdoor displays that do more than deliver static visibility. They want flexible digital formats, better integration with scheduling and content management, and displays that can adapt to changing campaigns without requiring full hardware replacement. This is especially relevant in retail and transportation settings, where out-of-home visibility intersects with location-based marketing, event-driven messaging, and changing foot or vehicle traffic patterns. The underlying behavioral change is a preference for displays that can be actively managed as part of a broader media and communications strategy rather than treated as fixed infrastructure.
Cost structure and supply chain strategy form the fourth major driver. Outdoor LED billboard deployments are not commodity purchases; they involve customization across site conditions, mounting requirements, resolution needs, and environmental exposure. That makes procurement and engineering coordination central to commercial outcomes. At the same time, raw material exposure and component availability can influence project timing and pricing. Companies that develop clearer internal standards for modular designs, serviceability, and selective premium sourcing are better positioned to control installation risk and avoid performance shortfalls that can undermine customer confidence.
Competitive Landscape and Leading Strategies
The competitive field in the LED billboard market is concentrated enough that scale, product breadth, and deployment reputation matter, yet still open enough that specialization can create meaningful differentiation. Market leaders are not competing solely on price; they are competing on the reliability of outdoor performance, the manageability of the total installation process, and the ability to support customers after deployment. That combination is especially important because a billboard is both a physical asset and an ongoing advertising medium, so the post-installation experience shapes repeat business and network expansion.
Daktronics stands out as a manufacturer with strong visibility in outdoor LED video walls, dynamic digital billboards, and large-scale message displays for sports, transportation, and advertising. Its recent expansion through deployment partnerships illustrates a practical growth model: extending reach by integrating hardware into broader outdoor advertising networks rather than relying only on direct product sales. This kind of network-centric expansion is strategically important because it ties the manufacturer more closely to live installation demand and long-term operational use.
Watchfire Signs competes with a focus on OOH digital billboards and outdoor LED signs supported by proprietary color calibration and specialized software for high-visibility advertising. In a market where perceived image quality and consistency influence buyer confidence, this software-and-calibration emphasis is a clear differentiation path. It signals an understanding that outdoor advertising performance depends on repeatable visual quality as much as on enclosure durability.
Formetco illustrates a different strategic angle: in-house manufacturing of LED digital billboards and sports systems, combined with product features such as long brightness warranties and fanless cooling. The wider agreement with SignBird to provide a modern marketing resource platform also shows how hardware companies are increasingly extending into customer-facing platforms and services. This is a useful indicator of where the industry is heading: manufacturers that can pair hardware reliability with streamlined customer acquisition, configuration, and deployment support may gain a stronger commercial position.
Samsung Electronics and its associated display offerings bring global scale, AI-driven content optimization, and ultra-high-brightness module capabilities into the market. Prismview, as a specialized provider of large-format LED signs and digital billboards operating under Samsung Electronics, represents how brand ecosystems can combine broad technology capability with focused go-to-market niches. For buyers, this structure can reduce uncertainty about supplier continuity and technical support, while also providing access to advanced display features that may be harder for smaller specialists to replicate on their own.
Planar Systems adds another dimension by emphasizing fine-pitch LED video walls and outdoor displays with U.S.-based calibration for premium corporate and advertising applications. This points to a market segment where installation quality, calibration rigor, and premium positioning matter more than volume alone. In practice, the existence of this kind of offering suggests that the LED billboard market is not uniform; there are clearly differing expectations between mass outdoor advertising use cases and higher-end, specification-driven deployments.
The broader competitive trend is a combination of consolidation pressure and segmentation. On one hand, larger players with manufacturing depth, brand recognition, and software or ecosystem capabilities are well placed to capture share in complex, multi-site, or higher-specification projects. On the other hand, specialized firms can still win by focusing on particular applications, regional procurement cycles, or distinctive product features such as long warranties, fanless designs, or calibration-led quality control. New entrants will find the greatest traction not by competing generally, but by solving a specific deployment pain point: faster permitting support, more predictable installation costs, improved content management integration, or stronger supply reliability for critical components.
Future Trends and Commercial Opportunities
One of the clearest trends for the next three to five years is the continued shift from hardware-only selling to integrated outdoor display solutions. Buyers increasingly expect a combination of reliable brightness, consistent color performance, content optimization tools, and serviceability over time. The commercial opportunity here lies in bundling hardware with software, maintenance, and deployment support in ways that reduce total cost of ownership and improve campaign effectiveness. Companies that can make outdoor billboards easier to operate and easier to measure will be better positioned to win multi-site contracts and long-term partnerships.
PW Consulting
A second trend is the growing importance of regional procurement and regulatory readiness as competitive factors. As signage compliance expectations evolve and project approvals become more detailed, speed to installation will depend on how well suppliers and operators align with local requirements. This favors organizations that standardize documentation, installation practices, and product labeling in a way that can be adapted across jurisdictions. The opportunity is to reduce friction in public procurement, leasing, and site development by making compliance part of the product story rather than a separate administrative burden.
LED Display Market
A third trend is the widening gap between premium and standard offerings. High-end components remain a meaningful cost driver, and certain applications will continue to justify higher specifications for brightness, durability, and visual consistency. At the same time, price-sensitive deployments will still seek dependable mid-tier solutions. The strategic implication is that successful players will need clear product tiering and transparent value propositions, so customers understand what they are buying and why one configuration is appropriate for a high-traffic transportation corridor while another fits a retail environment with different viewing conditions. Blurring these distinctions tends to create disappointed buyers and eroded margins.
These trends create several practical commercial opportunities. Manufacturers can pursue longer warranty structures, fanless or low-maintenance thermal designs, and more modular architectures that simplify upgrades and repairs. Operators and media owners can focus on network expansion in regions where permitting pathways are predictable and where digital billboard networks can be tied to recurring advertising demand. Technology providers can strengthen their position by improving content optimization, calibration consistency, and remote management tools that make large outdoor networks more efficient to run. In each case, the opportunity is not simply to sell more screens, but to make each installation more commercially effective over its lifespan.
There are also risks that should not be overlooked. Trade policy uncertainty can affect component costs and lead times, especially for cabinets and structural materials. Supply disruptions for high-end parts can delay projects or force design compromises. Regulatory changes can increase documentation and installation burdens. In addition, overly aggressive pricing strategies can pressure margins in a market where installation complexity and service expectations are rising. The most resilient strategies will be those that build flexibility into sourcing, keep product specifications aligned with real deployment conditions, and avoid assuming that growth in installed base automatically translates into profitable operations.
Decision-Maker Actions
For manufacturers, the priority is to strengthen the link between product design and real-world installation economics. That means investing in modular designs, service-friendly architectures, and clear product differentiation around brightness consistency, calibration, and long-term reliability. It also means preparing for component cost volatility through sourcing diversity and realistic lead-time planning. Firms that can reduce installation uncertainty and support predictable maintenance will have an advantage when buyers compare alternatives with similar screen specifications but different risk profiles.
For investors, the key question is whether a company’s revenue model is aligned with durable demand rather than one-time project cycles. Attention should be paid to recurring service potential, software and content-related value, regional exposure, and the ability to win public procurement or network expansion deals. Companies with strong post-installation support, clear compliance readiness, and recognizable branding in transportation, retail, sports, or premium corporate environments are more likely to benefit from the market’s steady growth path. Conversely, businesses that depend heavily on price competition without corresponding operational discipline may face tighter returns as installation and compliance costs rise.
For buyers and procurement teams, the most important discipline is to evaluate outdoor LED billboards as long-lived assets with operating implications, not as isolated hardware purchases. Site conditions, mounting complexity, resolution requirements, content management needs, and local compliance expectations should all be factored into the decision. Where possible, standardize specifications across projects to improve procurement predictability, and ask explicit questions about calibration practices, warranty coverage, thermal design, and support response. In a market where customized installations can vary significantly in scope and cost, clarity at the planning stage is one of the most effective ways to protect both budget and performance outcomes.
For organizations seeking a more detailed view of segment dynamics, regional variation, company-level positioning, and scenario-based forecasts, the full research report provides deeper segmentation detail and customized guidance. In a market where execution risk, regulatory readiness, and supply resilience are becoming as important as headline growth, access to granular market intelligence can help decision-makers move from general trend awareness to concrete commercial choices.
Outdoor LED Display Market
For detailed analysis of this topic, please visit the official page: LED Billboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Asia Pacific’s Drive is Redefining Water-Based Polyurethane Dispersions Growth
By pmarketresearch, 2026-09-21
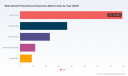
The Water-Based Polyurethane Dispersions Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global market for water-based polyurethane dispersions (PUDs) has entered a phase of steady expansion, with total revenue estimated at approximately 159.5 million USD in 2025 and a projected compound annual growth rate of 5.9 percent through 2032. This trajectory reflects a market that has largely moved past the volatility of the post-pandemic recovery period and is now driven by structural shifts in end-use industries. Historical growth between 2020 and 2025 has been consistent, with annual revenue climbing from roughly 125 million USD to the current level, indicating that the transition away from solvent-based systems is no longer a niche preference but a mainstream industrial requirement. Forward momentum is expected to continue as capacity additions and formulation refinements compound, pushing the market toward an estimated 236.6 million USD by 2032.
Despite this favorable direction, the industry faces several structural bottlenecks that will define competitive outcomes over the next several years. First, raw material cost volatility remains a persistent pressure point. Feedstock prices for polyols and isocyanates have experienced regional fluctuations, and even modest increases can compress margins for formulators who operate on thin spreads. Second, regulatory tightening around volatile organic compound emissions has raised the performance threshold for water-based alternatives. While compliance drives adoption, it also forces manufacturers to invest in advanced stabilization, dispersion, and crosslinking technologies to meet both environmental standards and end-user durability expectations. Third, the market exhibits a high degree of concentration, with a small group of large players accounting for the majority of revenue. This concentration creates pricing influence and technology leverage for incumbents, but it also leaves room for specialized and regional entrants to capture value through tailored formulations, faster customer support, and localized supply chains.
Together, these factors create a market that is growing, but not uniformly. Success will depend on navigating cost structures, meeting stricter performance criteria, and positioning offerings in segments where differentiation is possible.
Key Growth Drivers
The expansion of the PUD market is being propelled by a convergence of technological, regulatory, demand-side, and supply chain dynamics. Each of these forces reinforces the others, creating a self-sustaining cycle of adoption and innovation.
Technological Innovation and Formulation Advances
Formulation science has become a primary differentiator in a market where base chemistry is increasingly treated as a commodity. Recent product introductions underscore the shift toward multifunctional dispersions that combine low environmental impact with enhanced mechanical and chemical performance. For example, new wood coating dispersions launched in 2025 have been engineered to deliver outstanding protection for both residential and commercial surfaces, addressing the long-standing perception that water-based systems lag behind solvent-based counterparts in durability. At the same time, low-VOC and low-CO2 formulations enabled by mass-balance approaches are entering commercial production, allowing manufacturers to reduce the carbon footprint of existing application categories without sacrificing process compatibility. These advances matter because they expand the addressable market: rather than competing only in applications where water-based chemistry is the least-cost option, PUD suppliers can position their products in higher-value uses where performance parity or superiority is required.
Policy and Regulatory Environment
Regulatory frameworks continue to be a decisive force in reshaping demand patterns. Stricter VOC emission standards in the United States and Europe have accelerated the replacement of solvent-borne systems with low-VOC water-based alternatives, particularly in architectural coatings, construction-related applications, and industrial finishes. Compliance is no longer a peripheral concern; it is a commercial catalyst that shortens decision cycles for formulators under pressure to meet environmental targets. This regulatory momentum is also reshaping regional investment patterns, as companies look to establish or expand capacity closer to end markets to reduce exposure to logistics bottlenecks and to align with local compliance expectations. The net effect is a policy environment that favors scale, technical readiness, and the ability to provide documented environmental benefits alongside performance guarantees.
Worldwide Modified Polyurethane Dispersion Market
Demand-Side Shifts in End-Use Industries
End-use industries are driving change from the customer side as well. Coatings remain the largest application category, reflecting broad adoption across construction, furniture, and industrial substrates. Adhesives and sealants represent another major demand center, where water-based dispersions are increasingly specified for their ease of handling, reduced odor, and compatibility with sensitive substrates. Synthetic leather production has also emerged as a significant growth area, benefiting from the broader trend toward more sustainable material inputs in footwear, automotive interiors, and consumer goods. Flexible packaging and other specialty applications add further layers of demand, particularly where water-based systems can deliver adhesion, flexibility, and barrier properties without relying on solvent-intensive processes. Across these segments, the common thread is a preference for chemistries that support sustainability claims without compromising processing efficiency or final product quality.
Supply Chain and Cost Structure Evolution
Supply chain resilience has become a strategic priority, influencing both sourcing decisions and capacity placement. Recent capacity investments in Asia-Pacific reflect a deliberate effort to diversify production geography and reduce dependence on concentrated feedstock sources. This regional expansion is partly a response to trade dynamics and the desire to mitigate exposure to export controls and tariff-related risks on petrochemical feedstocks. At the same time, the growing use of bio-based polyols and renewable feedstocks is altering cost structures and sustainability profiles simultaneously. While bio-based inputs can introduce challenges in consistency and scale, they also offer a pathway to differentiate products on environmental grounds and to insulate part of the value chain from fossil-based price swings. The interplay between regional capacity growth and feedstock innovation is reshaping how cost, performance, and sustainability are balanced in commercial formulations.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive structure of the PUD market is characterized by a mix of global specialty chemical producers, regional scale players, and highly focused custom formulators. This mix creates a layered competitive environment where broad portfolio strength, regional responsiveness, and application-specific expertise all play roles in market positioning.
Strategic Positioning of Key Players
Several companies illustrate the range of strategies currently shaping the market. Large global producers are leveraging integrated feedstock capabilities and broad formulation portfolios to serve multiple end-use segments, with an increasing emphasis on low-VOC and bio-based grades. Their advantage lies in the ability to offer consistent supply, technical support at scale, and the credibility that comes with established brand recognition across coatings, adhesives, and construction applications. Other global suppliers have built strong positions around low-emission and high-performance formulations for fiber sizing, coatings, and industrial uses, using product lines that are closely associated with specific performance attributes. Integrated manufacturers with in-house polyol and isocyanate capabilities are particularly well placed to manage cost and supply continuity, while also tailoring dispersions for coatings and specialty applications. In the wood coatings and industrial finishes space, suppliers have focused on durability and chemical resistance as core selling points, launching products that target demanding residential and commercial environments.
At the same time, cost-competitive producers with integrated MDI operations are expanding capacity to serve coatings and adhesives markets, using scale and regional footprint as key levers. Specialist manufacturers have carved out roles by concentrating on biobased and renewable dispersions, custom design for adhesives and leather finishes, and specialty grades for graphic arts and technical applications. This segmentation allows smaller players to compete on agility, formulation tuning, and direct customer collaboration, even in a market where overall concentration is high.
Recent Developments Reshaping the Field
Recent activity in 2025 highlights how strategy is being translated into concrete capacity and product moves. A major Chinese producer completed a large water-based resin project that included substantial annual volume for waterborne polyurethane dispersions alongside epoxy resin capacity, reinforcing the trend of region-based expansion and feedstock integration. A German heavyweight started up a new production line focused on low-VOC and low-CO2 dispersions for architectural coatings and construction industries, signaling the importance of sustainability-linked product lines in mature markets. A European specialty player inaugurated a new PUD manufacturing facility in Singapore to better serve the Asia Pacific region, illustrating how incumbents are positioning capacity closer to fast-growing demand centers. In addition, a new wood coating dispersion was introduced to strengthen protection performance in residential and commercial applications, and a major Japanese chemical group announced significant capacity expansion for its polyurethane dispersion line. These developments collectively point to a market where investment is targeted at both scale and differentiation, with geography and performance attributes guiding where new capacity is placed.
Evolution of the Competitive Structure
The market is likely to continue evolving along two complementary paths. On one hand, consolidation pressure will persist among suppliers that need scale to sustain R&D investment, reduce feedstock exposure, and compete in regulated application areas. On the other hand, differentiation will deepen as customers demand formulations tailored to specific substrates, processing conditions, and sustainability targets. New and regional entrants can find openings by focusing on application niches, offering faster formulation turnarounds, or combining regional production with specialized bio-based or low-emission chemistries. The most resilient competitors will be those that can operate at both levels: maintaining broad supply reliability while also delivering specialized value where generic commodity dispersions are insufficient.
Future Trends and Opportunities
Looking ahead to the next three to five years, several trends are likely to define the direction of the PUD market and the opportunities within it.
Acceleration of Low-Emission and Bio-Based Formulations
The combination of regulatory pressure, customer sustainability commitments, and technological progress will continue to accelerate adoption of low-VOC and renewable feedstock-based dispersions. This trend creates opportunities for suppliers that can document environmental benefits, maintain performance parity, and offer drop-in compatibility with existing production lines. It also raises the bar for marketing claims: credible sustainability positioning will increasingly depend on transparent feedstock sourcing, lifecycle considerations, and independently verifiable performance data. Companies that can align product development with these expectations will be better placed to capture premium positions in coatings, adhesives, and synthetic leather applications.
Regional Capacity Build-Out and Supply Chain Rebalancing
Continued capacity additions in Asia-Pacific and selective investments elsewhere suggest that supply chains will become more regionally diversified. This rebalancing can reduce lead times, improve service levels, and lower exposure to trade-related disruptions, but it also requires disciplined execution to avoid overcapacity in specific segments. For buyers, the practical implication is greater choice and potentially stronger negotiating leverage, especially where regional suppliers can match performance with local support. For manufacturers, the opening lies in securing long-term offtake relationships and aligning capacity expansion with genuine end-use demand rather than speculative growth.
Performance Parity as the New Baseline
As water-based dispersions increasingly match solvent-based systems in durability, chemical resistance, and adhesion, the competitive conversation will shift from environmental compliance alone to total cost of ownership, processing efficiency, and application reliability. This shift favors suppliers with strong technical service, reliable quality consistency, and formulations that reduce rework or enable faster line speeds. It also creates an opportunity for hybrid and specialty dispersions that address specific substrate challenges, particularly in coatings and adhesives where performance requirements are tightening.
Polyurethane Dispersions (PUD) Market
Potential risks remain. Raw material price volatility can still erode margins if not managed through hedging, vertical integration, or value-based pricing. Regulatory requirements may continue to become more demanding, requiring ongoing reformulation and documentation efforts. In addition, the concentration of the market means that a few large players can influence pricing and availability, which can pressure smaller suppliers unless they have clear differentiation. Finally, capacity expansion must be carefully matched to demand absorption; overspending on volume in segments with limited differentiation could lead to price erosion.
Actionable Recommendations for Decision Makers
For Manufacturers and Formulators
Focus formulation development on the intersection of compliance and performance. Low-VOC and bio-based attributes open doors, but they must be paired with durability, adhesion, and processing reliability that reduce total application cost. Invest in technical service capabilities, because customers increasingly evaluate suppliers on the basis of formulation support and consistency as much as on base pricing. Where possible, strengthen feedstock linkage or long-term supplier agreements to dampen cost volatility and protect margin during periods of regional price movement.
For Investors
Evaluate companies based on how well they balance scale, differentiation, and regional positioning. Capacity expansion is only valuable if it is aligned with end-use demand and supported by product-level differentiation that protects pricing. Pay attention to companies that are building low-emission, mass-balance, or bio-based lines, since these investments are likely to become more valuable as regulatory and customer requirements tighten. Also consider the importance of regional footprint: suppliers with production located closer to fast-growing demand centers may gain service and resilience advantages that translate into better commercial outcomes over time.
For Procurement and Sourcing Leaders
Diversify sourcing options where feasible, especially by evaluating regional suppliers that can offer comparable performance with reduced logistics exposure. Use sustainability and compliance credentials as part of the evaluation framework, but verify performance claims through application testing before making sourcing changes. Build relationships with suppliers that provide formulation customization and technical support, since these capabilities can reduce implementation risk when transitioning from solvent-based or legacy water-based systems to advanced PUD grades.
Moving Toward a More Informed Strategy
The water-based polyurethane dispersions market is at a point where growth, regulation, technology, and supply chain strategy are tightly intertwined. Macro momentum is clear, but the commercial winners will be determined by how well companies navigate feedstock volatility, meet rising performance expectations, and position capacity where demand is expanding fastest. Detailed segmentation data, regional comparisons, and company-level assessments can help decision makers move from broad trends to specific, actionable plans. For organizations that need a deeper view of segment dynamics, competitive positioning, and forward scenarios, the full research report provides a structured foundation for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Water-Based Polyurethane Dispersions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
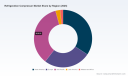
Refrigeration Compressor Market: Strategic Trends and Commercial Opportunities Through 2032
The refrigeration compressor market is undergoing a structural transformation that extends well beyond incremental efficiency gains. Over the historical period from 2020 to 2025, global revenue expanded from 20.0 billion USD to 28.79 billion USD, reflecting steady demand growth across residential, commercial, and industrial applications. Looking ahead, the market is projected to reach 47.12 billion USD by 2032, supported by a compound annual growth rate of 7.19 percent from 2026 to 2032. This trajectory signals a market that is not merely expanding but being reshaped by technological disruption, regulatory realignment, and shifting supply chain expectations. For executives and investors, the opportunity lies in understanding where value is migrating and how to position operations before the next wave of regulatory and technological inflection points.
Market Landscape and Current Structural Challenges
The market’s growth profile over the past five years has been consistent, but the composition of that growth reveals underlying tensions. Revenue progression from 23.33 billion USD in 2022 to 25.95 billion USD in 2024, followed by 28.79 billion USD in 2025, indicates that demand is no longer being driven solely by volume expansion. Instead, value creation is increasingly tied to product differentiation, refrigerant compatibility, and energy performance. The forward forecast shows a notable acceleration in later years, with revenue moving from 31.3 billion USD in 2026 to 47.12 billion USD in 2032. This pattern suggests that the market is entering a phase where technological upgrades and regulatory compliance will act as growth multipliers rather than cost burdens.
Several structural challenges are shaping how manufacturers, suppliers, and end users navigate this environment.
High Market Concentration and the Cost of Differentiation
The industry remains concentrated, with the top three players holding approximately 62 percent of revenue and the top five firms accounting for roughly 73 percent. This concentration creates a dual dynamic. On one hand, it provides scale advantages in procurement, engineering, and global distribution. On the other hand, it places pressure on smaller and mid-tier manufacturers to justify their positioning through specialized applications, regional responsiveness, or technology niches. In a market where differentiation increasingly depends on refrigerant readiness, variable-speed performance, and control integration, concentration can both stabilize and constrain competitive entry.
Regulatory Uncertainty Around Refrigerant Transition Timelines
The regulatory environment is a major source of both direction and ambiguity. Proposed adjustments to installation deadlines and pending GWP limits have introduced timing uncertainty for system builders and component suppliers. When compliance timelines shift, product roadmaps, inventory planning, and customer adoption cycles must be recalibrated. This creates an environment where strategic flexibility matters more than rigid long-term commitments. Manufacturers that can serve multiple refrigerant pathways while maintaining efficiency and reliability are better positioned to absorb regulatory revision without losing momentum.
Cost Pressures Across the Cold Chain and Components
Operational cost dynamics are rising across refrigerated logistics and related infrastructure. In the United States, refrigerated warehouse expenses increased in the third quarter of 2025 relative to the prior year, with electricity costs and labor costs both moving higher. These pressures do not stay confined to facilities; they flow back into equipment selection, where energy efficiency, maintenance intervals, and compressor reliability become commercial decision factors rather than purely technical specifications. For compressor suppliers, this means that performance claims must be tied to total cost of ownership, not just unit-level pricing.
Key Drivers Shaping Market Direction
The growth of the refrigeration compressor market is being pulled by a convergence of forces. Technology innovation, regulatory alignment, demand-side behavior, and supply chain realities are interacting in ways that change both product design and commercial strategy.
Technology Innovation and the Move Toward Higher Efficiency
Technological advancement is one of the clearest value-creation channels in the market. Recent developments illustrate how quickly product leadership can shift when efficiency, refrigerant compatibility, and capacity coverage align. At AHR Expo 2026, Garrett Motion unveiled an oil-free centrifugal compressor technology for HVAC systems with a portfolio spanning 7 to 500 tons of cooling capacity. This kind of platform expansion matters because it addresses a broader range of applications while removing oil-related maintenance concerns and supporting cleaner system architectures.
In parallel, compressor innovation is increasingly tied to refrigerant pathways and system-level performance. Copeland was recognized with the AHR Expo 2026 Innovation Award in the refrigeration category for transcritical CO2 scroll compressors featuring dynamic vapor injection technology. This points to a broader industry movement in which natural and low-GWP refrigerants are being integrated into compressors designed to manage higher pressures and more complex thermodynamic conditions. The strategic implication is that compressor value is moving from mechanical compression alone toward integrated system performance, including refrigerant handling, modulation, and efficiency across part-load conditions.
Worldwide Compression Refrigeration Machine Market
Policy and Regulatory Environment as a Design Constraint and Catalyst
Regulation is not simply a compliance checklist; it is reshaping engineering priorities and product portfolios. The U.S. Energy Policy and Conservation Act establishes stringent energy standards for equipment, encouraging adoption of newer oil-free and higher-efficiency technologies. At the same time, regulatory adjustments have introduced timing complexity. A proposed EPA rule from October 2025 removed the installation deadline for R-454B systems in the residential and light commercial AC and heat pump subsector to address supply chain issues. EPA also proposed delays to pending new system GWP limits of 150 and 300 that were set to take effect starting in 2026 and 2027.
These developments create a practical strategic tension. On one side, energy standards and refrigerant goals continue to push manufacturers toward cleaner and more efficient designs. On the other side, deadline adjustments can slow near-term adoption cycles and complicate demand forecasting. The market response is likely to favor companies that maintain flexible product platforms, invest in multiple refrigerant-ready solutions, and communicate total efficiency benefits in ways that remain compelling even if regulatory timing changes.
Refrigerant Compressors Market
Demand-Side Shifts Toward Reliability, Efficiency, and Cold Chain Growth
End-user behavior is changing in ways that reinforce long-term compressor demand while altering the basis of purchase decisions. Cold chain expansion remains a central theme because refrigerated storage, distribution, and temperature-sensitive logistics continue to grow in importance across food, pharmaceutical, and industrial supply chains. As operational costs rise, end users pay greater attention to components that reduce energy consumption, extend service intervals, and improve part-load performance.
In residential and light commercial settings, consumer expectations increasingly link comfort, efficiency, and environmental impact. This does not automatically translate into demand for a single compressor type; rather, it pushes manufacturers toward systems that can meet efficiency targets without sacrificing reliability or serviceability. The broader lesson is that demand growth is becoming more quality-sensitive. Volume alone is no longer the dominant value driver; performance consistency, compatibility with evolving refrigerants, and integration with controls are becoming commercially decisive.
Supply Chain and Cost Structure Dynamics
Supply chain structure is becoming a strategic variable rather than a background condition. High-efficiency permanent magnet motors used in variable-speed compressors depend on rare earth elements such as neodymium and dysprosium, with supply concentrated in sources tied to China. This dependency creates exposure to price volatility, sourcing constraints, and geopolitical risk. For compressor manufacturers, the challenge is twofold: maintain performance leadership associated with advanced motor and variable-speed designs while managing material exposure through design alternatives, supplier diversification, and inventory planning.
Cost structure is also being shaped by labor, electricity, and logistics dynamics. As refrigerated warehouse expenses rise across electricity and labor lines, the downstream effect is greater scrutiny of equipment that influences energy draw and maintenance labor. Compressors that support efficient operation under variable conditions can reduce exposure to these rising operating costs, making energy performance a direct financial consideration rather than a compliance feature.
Competitive Landscape and Leading Strategies
The competitive environment reflects both entrenched scale and ongoing specialization. Firms are pursuing distinct routes to value: some emphasize broad commercial and industrial coverage, others focus on hermetic and light commercial solutions, and a growing number are differentiating through refrigerant readiness and energy efficiency.
Strategic Positioning Across Leading Manufacturers
BITZER continues to position around semi-hermetic and open-drive reciprocating compressors as well as screw compressors for commercial and industrial refrigeration. This scope gives it relevance in higher-duty applications where robustness, serviceability, and system flexibility matter. Secop’s specialization in hermetic compressors for light commercial refrigeration and mobile cooling creates a different value proposition, centered on compact, application-specific solutions. Frascold manufactures semi-hermetic reciprocating compressors for HVACR and refrigeration systems, with recent activity including new electrical box validation for semi-hermetic compressors, an indication of ongoing attention to electrical integration and reliability.
Danfoss offers reciprocating, scroll, and BOCK compressors for commercial refrigeration with a clear emphasis on energy efficiency and natural refrigerants. That positioning aligns with the broader market shift toward low-GWP solutions and efficiency-driven selection. Embraco provides reciprocating and scroll compressors for refrigeration in both fixed-speed and variable-speed applications, and its December 2025 inauguration of a new production line for FMS compressors at its Joinville plant adds capacity for up to 5 million units per year. This expansion signals a strategic push to strengthen supply capacity and responsiveness in variable-speed and residential-adjacent segments.
Copeland supplies scroll compressors and condensing units for commercial and industrial refrigeration systems, and its recognition for transcritical CO2 scroll compressors with dynamic vapor injection technology underscores the strategic importance of refrigeration architectures that can handle natural refrigerant challenges. Dorin produces semi-hermetic reciprocating compressors and condensing units for refrigeration and air conditioning, supporting a portfolio approach that spans multiple application types. GMCC develops and manufactures reciprocating, rotary, and scroll compressors for refrigeration and air conditioning, reflecting a broad product footprint that can support both cost-competitive and technology-diverse market needs.
Differentiation Themes in a Concentrated Market
Across these players, several differentiation themes are emerging.
- Refrigerant and regulatory readiness: capability across multiple refrigerant pathways, including natural and low-GWP options, is increasingly a competitive requirement rather than a niche advantage.
- Efficiency under real operating conditions: part-load performance, variable-speed modulation, and system-level efficiency are becoming more important than nominal ratings alone.
- Application breadth versus specialization: some firms compete through wide coverage across commercial and industrial uses, while others compete through focused solutions in hermetic, light commercial, or mobile cooling applications.
- Supply capacity and regional responsiveness: production expansion and localized manufacturing can improve availability and reduce lead-time risk in markets where demand cycles are sensitive to regulatory or seasonal shifts.
- Electrical and control integration: validation of electrical components and compatibility with advanced controls can differentiate compressors in systems where reliability and serviceability are purchasing priorities.
Market Evolution: Consolidation, Segmentation, and New Entry Pressure
The market’s concentration suggests that consolidation and partnership will remain relevant, especially for companies seeking scale in procurement, distribution, or technology development. At the same time, segmentation is creating space for specialists. Hermetic, scroll, semi-hermetic, and open-drive solutions are not competing in a single uniform market; they are serving different duty profiles, refrigerant environments, and service expectations. This segmentation allows new entrants and mid-tier players to compete by targeting specific application pain points rather than trying to match broad-line scale directly.
New entry pressure is likely to be most significant where technology shifts open performance gaps. Oil-free centrifugal platforms, advanced scroll architectures for natural refrigerants, and variable-speed motor integration all create opportunities for companies that can deliver credible performance in a narrower domain. Conversely, in mature segments with tight margins, scale, service networks, and refrigerant compliance will remain strong barriers.
Forward Trends and Commercial Implications for 2026 to 2032
Combining market growth projections with current technology and regulatory dynamics points to several trends that will shape commercial strategy over the next three to five years.
Trend 1: Efficiency and Refrigerant Compatibility Will Redefine Product Value
As energy standards tighten and refrigerant transitions continue, compressor value will be judged more by real-world efficiency and refrigerant readiness than by basic mechanical function. The forward revenue path from 31.3 billion USD in 2026 to 47.12 billion USD in 2032 implies not only volume growth but also rising average value per unit in segments where performance and compliance are strongest. Commercial opportunity lies in platforms that can serve multiple refrigerant routes while maintaining efficiency, reliability, and serviceability. The risk is that product portfolios become fragmented if companies treat refrigerant transition as a series of one-off adaptations instead of a structural design shift.
Trend 2: Variable-Speed and Advanced Motor Systems Will Expand in Importance
Variable-speed applications and high-efficiency motor designs are expected to gain commercial prominence as end users seek to reduce energy exposure and improve part-load performance. This trend aligns with broader development activity and with demand-side pressure from rising electricity and labor costs in refrigerated operations. The strategic opportunity is to offer compressors that deliver meaningful modulation and efficiency benefits without introducing excessive complexity or service burden. The principal risk is material exposure and supply continuity for rare earth-dependent motor technologies, which may require design diversification or sourcing strategies that reduce single-source vulnerability.
Trend 3: Production Expansion and Regional Capacity Will Shape Availability and Speed to Market
Capacity expansion, such as Embraco’s new line for FMS compressors, indicates that manufacturers are investing in throughput and regional responsiveness. In a market where regulatory timing, cold chain demand, and technology upgrades can create shifting demand peaks, availability and lead time become competitive factors. Companies that can scale selectively while maintaining quality and refrigerant compatibility will be better positioned to capture demand during transition periods. The uncertainty here lies in whether capacity investments match the pace of demand shifts, especially if regulatory timelines continue to adjust or if raw material constraints affect output planning.
Associated Commercial Opportunities and Risks
These trends create opportunity in several areas.
- Designing modular or multi-refrigerant-ready platforms that can adapt to changing compliance timelines without full redesign cycles.
- Linking compressor offerings to total cost of ownership arguments, especially in commercial and industrial settings where electricity and labor costs are rising.
- Expanding capacity and supply resilience in segments where demand is sensitive to cold chain growth, residential efficiency expectations, or regulatory-driven replacement cycles.
- Developing service and control integration capabilities that make compressors easier to deploy, monitor, and maintain in advanced systems.
At the same time, risks remain. Regulatory timing volatility can disrupt adoption curves. Material dependencies can create cost and availability shocks. Concentration in the market can make it harder for smaller players to secure shelf space unless they bring clear differentiation. And efficiency expectations can rise faster than the practical ability of some systems to deliver consistent performance across diverse operating conditions.
Strategic Actions for Decision Makers
For manufacturers, investors, and procurement leaders, the market environment calls for actions that balance technology ambition with operational resilience.
For Manufacturers
Prioritize platforms that can support multiple refrigerant pathways and efficiency targets without abandoning service reliability. Where variable-speed and advanced motor designs are part of the roadmap, manage rare earth exposure through design alternatives, supplier diversification, and long-term sourcing agreements. Use capacity investments selectively to protect availability in growth segments rather than expanding uniformly across all product lines. Strengthen validation and electrical integration work, because reliability and serviceability are increasingly decisive where energy performance claims must hold up in real-world operation.
For Investors
Look beyond headline market growth and focus on where value is migrating within the market. Companies with credible positions in natural refrigerant technologies, variable-speed efficiency, and application-specific refrigeration solutions are likely to capture higher-value demand as regulatory and operational pressures intensify. Evaluate exposure to raw material dependencies, production scalability, and the ability to navigate regulatory timing changes. In concentrated markets, the most attractive opportunities may not always come from the largest names but from firms that can demonstrate differentiated technology, strong execution in targeted segments, or supply resilience that reduces disruption risk.
For Procurement and Sourcing Leaders
Procurement decisions should increasingly weigh total operating cost, refrigerant compatibility, and service implications alongside unit pricing. As electricity and labor costs rise in refrigerated operations, compressors that improve efficiency and reduce maintenance exposure can create meaningful downstream savings. Where possible, prioritize suppliers with clear roadmaps for regulatory alignment and proven capability across the refrigerant types expected in near-term deployments. In addition, assess supply continuity plans, particularly for technologies that rely on specialized motor materials or complex electrical integration, so that procurement strategy is not disrupted by material or capacity constraints.
Evaluating the Next Phase of Market Development
The refrigeration compressor market is moving into a period in which growth, technology, and regulation are intertwined. The projected expansion from 28.79 billion USD in 2025 to 47.12 billion USD by 2032 signals that demand will continue to rise, but the more important question for decision makers is where competitive advantage will be earned. The answer appears to lie in refrigerant-compatible efficiency, variable-speed performance, supply resilience, and the ability to translate technical performance into commercial reliability.
For organizations that need a more granular view of segment-level dynamics, regional demand patterns, and company-by-company positioning, a deeper research download is available for detailed breakdown and customized guidance. The broader strategic task now is to align product roadmaps, sourcing plans, and investment theses with the market’s shift toward cleaner, more efficient, and more adaptable refrigeration compressor solutions.
PW Consulting Automotive & Machinery Research Center
For detailed analysis of this topic, please visit the official page: Refrigeration Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
4A and Air Separation Drive the Molecular Sieve Adsorbents Market: 4.7% CAGR Analysis 2026-2032
By pmarketresearch, 2026-09-21
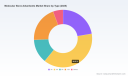
Molecular Sieve Adsorbents Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
The molecular sieve adsorbents market is entering a decisive growth phase. Valued at USD 1,118.0 million in 2020 and projected to reach USD 1,934.0 million by 2032, the sector is expanding at a compound annual growth rate of 4.7% throughout the 2026–2032 forecast period. This trajectory reflects more than steady industrial demand; it signals a structural pivot driven by energy transition priorities, tightening emissions standards, and technological maturation across gas separation, drying, and purification applications. For executives and investors operating in adjacent sectors, understanding where value is accumulating—and where margin pressure is intensifying—is no longer optional. The market’s evolution requires a clear view of demand drivers, competitive positioning, and the operational realities that will define winners over the next five years.
Market Landscape and Core Challenges
The market has grown from USD 1,237.4 million in 2023 to an estimated USD 1,402.0 million in 2025, a progression marked by consistent demand pull from industrial gases, refining, and specialty separation applications. Asia Pacific currently anchors the largest regional revenue share, followed by North America and Europe, while Latin America and the Middle East & Africa contribute smaller but steadily growing positions as regional industrial capacity expands. Type-wise, 4A-grade sieves command the broadest application footprint, 3A and 13X grades sustain strong positions in dehydration and gas drying, and 5A variants remain essential in higher-selectivity separation workflows. On the application side, air separation and petroleum refining together represent the dominant revenue streams, with petrochemicals and refrigerant processing forming a meaningful secondary layer of demand.
Beneath this growth curve, several structural challenges are reshaping how vendors, buyers, and investors should interpret market signals.
Raw material cost volatility is compressing margin stability. Sodium silicate and sodium aluminate prices have become increasingly sensitive to energy market fluctuations and supply chain disruptions. Since these precursors form the foundation of zeolitic sieve production, cost swings directly affect manufacturing economics and pricing strategies. Producers that lack diversified sourcing, long-term supply agreements, or process efficiencies are facing greater exposure, particularly in cost-sensitive industrial drying segments.
Regulatory tightening is raising the performance threshold. New environmental restrictions in the EU and the US require higher-purity molecular sieves capable of meeting ppm-level contaminant limits in air separation and related processes. At the same time, stricter volatile emissions rules are pushing buyers toward circular-economy procurement policies that favor regenerated sieves. These dynamics create a dual pressure: performance specifications are rising, while procurement teams are also scrutinizing lifecycle cost and sustainability credentials. Compliance with ISO 9001 and REACH standards further adds to certification costs for sieves used in pharmaceutical and food-grade applications, which raises the barrier to entry in high-value end markets.
Operational costs are reshaping competition in labor- and logistics-intensive segments. Rising labor and logistics costs for specialized adsorbent handling, transport, and regeneration have pressured margins in compressed air and industrial drying applications. In markets where sieves are treated as more commoditized consumables, buyers are increasingly evaluating total cost of ownership rather than unit price alone. This shift rewards suppliers that can offer reliable regeneration protocols, predictable service intervals, and optimized logistics over those competing purely on product pricing.
Key Demand Drivers Reshaping the Market
The market’s expansion is not uniform; it is being unevenly pulled by technological, regulatory, and demand-side forces. Three drivers stand out as particularly influential for the 2026–2032 period.
Technology innovation is expanding the addressable use cases
Advances in sieve formulation and manufacturing are extending the role of molecular sieves beyond traditional dehydration and separation. Higher-selectivity grades are increasingly relevant in hydrogen purification, carbon capture workflows, and battery-related drying applications, where moisture and contaminant control directly affect process efficiency and end-product quality. Improved 13X and lithium X variants are enabling more effective removal of specific impurities in natural gas and olefin/paraffin streams, while specialized grades designed for high-purity gas drying are opening opportunities in electronics, medical, and advanced materials processing. These innovations matter because they shift molecular sieves from a maintenance-driven consumable to a performance enabler in higher-margin applications.
Recent product and capacity actions illustrate this direction. One major supplier expanded its zeolite manufacturing facility in Ludwigshafen, Germany, to increase production of specialized molecular sieves for hydrogen purification and carbon capture applications. Around the same period, the same company introduced improved sieve grades tailored for drying lithium-ion batteries and high-purity gases. These moves signal a deliberate pivot toward applications where purity, consistency, and energy efficiency carry stronger commercial weight than bulk volume alone.
Environmental and regulatory pressure is accelerating adoption of cleaner separation technologies
Policy and regulatory environments are acting as both a constraint and a catalyst. Stricter emissions controls are forcing industrial users to improve the efficiency of gas drying, purification, and separation processes. In practical terms, this increases demand for sieves that can operate longer between regenerations, tolerate harsher process conditions, and meet increasingly stringent purity specifications. Regenerated-sieve procurement policies are also gaining traction as organizations seek to reduce waste and align purchasing with circular-economy goals. For suppliers, this means that performance claims, regeneration compatibility, and documentation of compliance are becoming integral parts of the commercial proposition rather than ancillary service features.
Demand-side shifts are broadening the customer base
Beyond traditional refining and air separation, demand is spreading into segments where gas purity and drying performance are becoming critical to product quality. Medical oxygen generation is one of the more visible examples, where reliable oxygen purity depends on consistent sieve performance. Growth in electrolyte and battery manufacturing processes is also increasing the need for moisture-sensitive drying solutions, and higher-specification industrial gas applications continue to expand in specialty chemicals and advanced materials. At the same time, procurement behavior in compressed air and industrial drying is shifting toward lifecycle value. Buyers are more willing to evaluate supplier reliability, regeneration support, and compliance documentation if those factors reduce downtime and total operating cost.
Supply chain and cost structure changes are redefining competitive dynamics
Cost pressures are not limited to raw materials. Energy-intensive production processes, specialized handling requirements, and logistics for regeneration and replacement create a cost structure that is increasingly sensitive to regional operating conditions. This favors producers with integrated manufacturing footprints, stable energy access, and the ability to standardize regeneration services or technical support. For buyers, it underscores the importance of supplier selection criteria that account for lead time consistency, regeneration efficiency, and technical guidance, especially where process interruptions carry high costs.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with the top three players accounting for approximately 29.8% of revenue and the top five representing around 38.6%. This level of concentration suggests that scale, application expertise, and geographic reach still matter, but it also leaves room for differentiated specialists to compete effectively in high-value niches. The competitive field is shaped by a mix of broad-portfolio suppliers and focused technology players, each pursuing distinct strategic plays.
Zeolite Molecular Sieves Market
Arkema has positioned itself as a global leader in Siliporite® molecular sieve adsorbents across 3A, 4A, 5A, and 13X grades. Its portfolio spans dehydration, purification, and separation for energy, chemicals, industrial gases, medical and pharma packaging, and construction applications. The company’s recent capacity expansion in Ludwigshafen and the launch of improved Hespera-grade sieves for lithium-ion battery drying and high-purity gases indicate a strategy centered on high-performance grades tied to hydrogen purification, carbon capture, and advanced battery-related drying. This approach allows Arkema to compete not just on volume but on application-specific performance and technical credibility.
BASF SE remains a major manufacturer of 3A, 4A, 5A, and 13X molecular sieve adsorbents for compressed air drying, petrochemical refining, and general industrial applications. Its strength lies in broad application coverage and deep integration with catalyst and chemical portfolios, which supports cross-selling and a strong presence in refining and industrial drying. BASF’s positioning suggests a strategy of scale, consistency, and breadth, appealing to buyers seeking reliable supply and established product familiarity.
PW Consulting
Honeywell UOP stands out through its UOP/MOLSIV® and HiSiv® molecular sieve adsorbents, which are focused on olefin/paraffin purification, natural gas processing, and polymer streams. This specialization gives Honeywell UOP a strong foothold in higher-value separation applications where selectivity and process integration are critical. Its strategy appears oriented toward performance differentiation and close ties to downstream process requirements, which can translate into stronger customer lock-in in technologically demanding segments.
Zeochem AG offers a wide range of 3A, 4A, 5A, 13X, lithium X, calcium X, and Purmol zeolite molecular sieve adsorbents for industrial oxygen generation, natural gas treatment, solvent drying, and medical oxygen. Zeochem has been particularly active in expanding its medical oxygen generation footprint, including an office expansion in Louisville, KY, to support growth of its ZEOtope molecular sieve product line. The company also completed the acquisition of SiliCycle Inc. to broaden its portfolio of high-value chromatography gels and molecular sieve technologies. These moves reflect a dual strategy: reinforcing leadership in medical and industrial oxygen applications while expanding into higher-margin specialty purification and chromatography-related technologies.
Tosoh Corporation supplies Zeolum® zeolite molecular sieve adsorbents for gas product drying, petrochemical refining, and separation processes. Its positioning is consistent with a steady, application-focused supplier serving refining and gas drying markets with established product lines and regional manufacturing strength. W.R. Grace & Co. continues to provide molecular sieve adsorbents and related adsorbent technologies for gas purification and refining applications, leveraging a long-standing reputation in process technologies. Albemarle Corporation integrates molecular sieve adsorbents within broader catalyst and specialty chemical portfolios, making it relevant in petrochemical and chemical processing contexts where integrated solutions can create additional value. Clariant AG supplies molecular sieve adsorbents for industrial drying, purification, and separation in chemicals and refining sectors, positioning around application reliability and specialty chemical expertise.
The competitive landscape is evolving along several axes. Consolidation is visible in targeted acquisitions, such as Zeochem’s purchase of SiliCycle, which expands technical breadth rather than simply adding volume. At the same time, capacity expansions are being directed toward higher-value applications, especially hydrogen purification, carbon capture, medical oxygen, and battery-related drying. This suggests a market that is not merely growing in size but also shifting in composition, with premium performance grades gaining relative importance. New entrants and specialty innovators can still compete by focusing on narrow applications where purity, regeneration efficiency, or compliance documentation provide a genuine advantage, but broaderscale competition will increasingly depend on manufacturing reliability, supply chain resilience, and application engineering capabilities.
Worldwide Zeolite Adsorbents Market
Forward Outlook: Trends Shaping the Next 3–5 Years
Based on current market dynamics and recent corporate actions, three trends are likely to define the next phase of market development.
Premium-grade molecular sieves will capture a growing share of value, even in a market that continues to expand in volume. Demand for higher-purity, more selective, and more durable sieve grades is rising in hydrogen-related workflows, carbon capture, medical oxygen, battery drying, and high-specification industrial gases. As stricter purity requirements and circular procurement practices become more common, buyers will place greater weight on performance consistency and regeneration efficiency. Suppliers that can demonstrate differentiated grades and reliable technical support are likely to retain stronger pricing power in these segments. The commercial opportunity lies in aligning product development with applications where contamination control and process reliability directly affect end-product quality and operating cost.
Regional demand will keep diversifying, but not uniformly. Industrial capacity growth in Asia Pacific continues to support expanding consumption, while North America and Europe maintain strong demand in refining, industrial gases, and regulatory-driven substitution. Latin America and the Middle East & Africa are expected to grow from smaller bases as regional petrochemical, refining, and industrial gas activities expand. The strategic implication is that supply footprints, logistics planning, and local technical support will become more important differentiators, especially where buyers value responsive service and consistent lead times over pure unit-cost competition.
Sustainability and circularity will move from policy language to procurement practice. Regenerated sieve adoption and waste-reduction expectations are likely to become more embedded in buyer decision-making, particularly in jurisdictions with stronger environmental mandates. This will increase the relevance of regeneration-compatible product design, service frameworks, and compliance documentation. At the same time, certification and compliance costs will remain a factor in pharmaceutical, food-grade, and other high-purity applications, reinforcing the importance of demonstrated quality systems. The opportunity here is not simply to sell sieves, but to offer predictable lifecycle solutions that reduce disposal, downtime, and compliance risk.
These trends carry potential risks. Raw material price volatility and energy market swings could continue to challenge cost structures, especially for producers without diversified sourcing or efficient manufacturing. Regulatory requirements may keep rising, raising the bar for performance and certification and potentially narrowing the field for less-equipped competitors. Demand for premium grades may accelerate faster than manufacturing capacity in certain niches, creating short-term supply tightness, while more commoditized segments could face continued margin pressure from total-cost-of-ownership buying behavior. Investors and operators should therefore watch not only top-line growth, but also the mix shift toward higher-value applications and the extent to which regeneration and service capabilities influence purchasing decisions.
Strategic Implications for Decision-Makers
The market’s direction suggests different priorities depending on a reader’s role in the value chain.
For manufacturers and technology providers, the imperative is to align capacity and R&D with higher-value applications rather than chasing bulk volume alone. Investments in hydrogen purification, carbon capture, medical oxygen, and battery-related drying appear better positioned for durable differentiation than undifferentiated commodity compete. Equally important is building or strengthening regeneration compatibility, technical service, and compliance documentation, since buyers in regulated and high-specification applications increasingly evaluate total cost of ownership and lifecycle reliability. Supply chain resilience—through diversified raw material sourcing, stable energy access, and logistics optimization—should be treated as a strategic asset, not just an operational concern, especially where sodium silicate and sodium aluminate volatility continues to affect margins.
For investors, the key question is where margin resilience and growth are converging. The market’s moderate concentration leaves room for both scaled incumbents and specialized players, but value creation is increasingly tied to application specificity, performance differentiation, and service-enabled revenue models. Capacity expansions directed at premium grades and higher-specification end markets are more likely to support pricing stability than volume-only plays in commoditized drying segments. Investors should also monitor consolidation activity and technology tuck-in acquisitions, as these can reshape portfolios quickly by adding chromatography gels, specialty purification capabilities, or new application footholds. Regulatory tailwinds and circular-economy procurement can expand demand, but they also raise entry barriers in food-grade, pharmaceutical, and high-purity applications, which may favor established, well-documented suppliers.
For procurement and operations leaders, the buying lens should shift from unit price to lifecycle value and risk reduction. In compressed air, industrial drying, and other labor- and logistics-sensitive segments, total cost of ownership is being shaped by regeneration efficiency, downtime risk, handling complexity, and compliance burden. Selecting suppliers with strong technical support, clear regeneration protocols, and reliable lead times can reduce hidden costs that are not always visible in initial pricing comparisons. Where sustainability or regulatory requirements are tightening, prioritizing regenerated-sieve compatibility and documented compliance can lower both operational and audit-related risk. In higher-purity applications, consistency of performance and contaminant control should carry more weight than baseline specification sheets, because ppm-level limits and process sensitivity can make variability far more expensive than the sticker price of the sieve itself.
Conclusion
The molecular sieve adsorbents market is expanding at a steady pace, but the more important story is how its center of gravity is shifting. Demand is moving toward higher-purity, higher-selectivity grades in hydrogen purification, carbon capture, medical oxygen, battery-related drying, and other application areas where performance directly affects product quality and operating efficiency. At the same time, cost volatility, regulatory tightening, and lifecycle-oriented procurement are reshaping how value is created and captured. Companies that combine application-specific innovation with reliable supply, regeneration support, and compliance credibility are better positioned to defend margins and capture growth than those competing primarily on volume.
For decision-makers seeking a more detailed view of segment-level dynamics, regional demand patterns, procurement implications, and company-level strategic scenarios, the full PW Consulting report provides deeper segmentation data and tailored recommendations across manufacturing, investment, and procurement perspectives.
For detailed analysis of this topic, please visit the official page: Molecular Sieve Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Power Connectors Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Size, Trajectory, and Pressing Challenges
The global power connectors market has evolved from a mature, steady-growth segment into a strategically critical component of electrification and digital infrastructure. Recent market tracking shows total revenue climbing from approximately 163 million USD in 2020 to roughly 215 million USD by 2025, with a forward trajectory shaping up toward 345 million USD by 2032. The implied five-year growth rate of 5.14 percent reflects more than incremental industrial expansion; it signals structural demand shifts driven by grid modernization, data center build-outs, and high-power mobility applications. This baseline momentum, however, sits alongside a market that remains comparatively fragmented, with the top three players accounting for less than 25 percent of total revenue and the top five just above that threshold. Such concentration levels indicate room for both consolidation and differentiated niche positioning rather than a single dominant paradigm.
Three structural challenges currently define the operating environment for manufacturers, buyers, and investors.
- Raw material volatility and cost pass-through pressure. Elevated prices for copper and precious metals have begun to compress margins and force repricing across connector portfolios. The impact is not uniformly absorbable, especially for standardized lines where substitution and value engineering are limited.
- Supply chain unpredictability in power-intensive components. Lead times for power supply manufacturing and related interconnect components remain sensitive to demand swings and supplier allocation practices. This instability complicates capacity planning for OEMs and system integrators who rely on predictable delivery windows.
- Regulatory and materials-access constraints. Export controls on certain rare earth materials and broader industrial policy shifts are reshaping sourcing options, qualification pathways, and timeline risk for high-performance connector programs. Companies must now evaluate not only performance and cost, but also material provenance and regulatory exposure.
The practical implication is that scale alone is no longer a sufficient competitive moat. Response speed to cost shocks, qualification agility, and the ability to secure reliable material channels are becoming equally decisive. Market participants that treat these pressures as purely tactical purchasing issues tend to lag; those that embed them into product architecture, supplier strategy, and customer contracting models are better positioned to preserve margin and share.
PW Consulting
Core Drivers Reshaping Demand and Value Creation
Several interlocking forces are steering the market beyond a simple volume-growth narrative.
High-current density and application-specific architecture
A defining technical shift is the move toward connectors engineered for higher current density, hybrid power-signal integration, and harsher operating conditions. Products capable of handling currents in the 350A to 500A range are increasingly visible in industrial electrification, energy storage interfaces, and high-density data center backplanes. This evolution is not just about larger contacts; it is about packaging, thermal behavior, vibration resilience, and modular mating systems that reduce integration risk. Recent product introductions from leading manufacturers illustrate this direction, including high-current connector lines targeting battery energy storage systems, sealed interconnects with combined power and signaling contacts for harsh environments, and vibration-resistant connectors designed for powertrain applications. The recurring theme is performance under constraint: more power in tighter spaces, greater durability, and safer maintenance access.
Policy, energy security, and infrastructure acceleration
Policy and energy-security dynamics are reshaping demand indirectly but powerfully. Industrial and grid infrastructure programs are accelerating the need for reliable electrical interconnects, while domestic production gaps in large power equipment have exposed how dependent downstream deployment schedules are on upstream component availability. When large transformers and related grid equipment face extended lead times, the pressure cascades into interconnected component markets and incentivizes sourcing strategies that prioritize resilience over lowest unit cost. In parallel, materials-access regulations are nudging engineering teams toward alternative material selections and more rigorous supplier qualification. The net effect is a market where compliance and supply assurance are increasingly part of the value proposition rather than background overhead.
Demand-side behavior: electrification, data centers, and ruggedized mobility
On the demand side, several application pockets are expanding the relevance of high-performance power connectors. Industrial automation and instrumentation continue to anchor demand, but growth is increasingly linked to electrified processes, energy storage integration, and networked equipment that blends power delivery with signaling integrity. Data centers and communication infrastructure are also intensifying requirements for dense, reliable interconnects that can support higher power throughput with stable performance. In mobility and aerospace contexts, demand is shaped less by volume and more by qualification difficulty, environmental resilience, and total cost of ownership over long service life. For commercial buyers, the strategic question is shifting from "what connector fits the spec" to "which connector architecture reduces integration risk, maintenance downtime, and future retrofit cost."
Automotive Connectors Market
Cost structure, material economics, and sourcing recalibration
Cost structures are being redefined by materials economics and production logistics. Persistent copper deficits and elevated precious metal prices are translating into documented price increases across connector portfolios, often in the low-to-mid single-digit range and higher for materials-intensive designs. At the same time, power supply manufacturing lead times remain uneven, meaning that inventory strategy, contract terms, and second-source development are becoming strategic levers rather than administrative tasks. This environment rewards companies that can negotiate multi-tier cost pass-through mechanisms, lock in critical material allocations, and design connectors that use materials more efficiently without sacrificing performance. It also rewards buyers who treat connector specification as a long-term sourcing decision, balancing unit price against delivery reliability and lifecycle risk.
Competitive Landscape: Positioning, Differentiation, and the Shape of Change
The competitive field is diverse, spanning broad portfolio players, application-focused specialists, and companies built around specific high-power niches. Rather than competing purely on price, leading firms are building differentiation through current-handling capability, modularity, environmental sealing, qualification depth, and integration support for complex systems.
TE Connectivity illustrates one strategic orientation: concentrating on high-current density solutions and hybrid connector architectures that serve industrial, data center, and energy storage use cases. Its recent product activity around higher-ampacity connectors and stacked hybrid interfaces for battery energy storage systems reflects a move toward ecosystems where power, signal, and packaging are addressed together. Amphenol Corporation leans into high-power backplane, card-edge, and high-power series that align with dense system architectures. Molex emphasizes specialty power connectors and high-performance data center and harsh-environment solutions, reinforcing the trend toward application-tailored portfolios. Hirose Electric Co., Ltd. continues to develop board-to-board, cable, and industrial high-current connectors, with recent launches emphasizing vibration resistance for powertrain environments. HARTING Technology Group has carved out a recognizable position in modular heavy-duty connectors for industrial electrification and automation, where maintainability and ruggedness are central purchase criteria. In higher-reliability corners of the market, Glenair, Inc. and Positronic Industries, Inc. focus on military, aerospace, and ultra-high power interfaces, often with touch-safe, waterproof, or blind-mate features that reduce integration risk. Anderson Power Products rounds out the landscape with sealed, high-power interconnect lines targeting data center and battery applications.
These profiles reveal several competitive patterns:
- Application-led differentiation is strengthening. Leaders are less likely to win on generic catalog breadth alone and more likely to win by aligning connectors with specific operating conditions, mating requirements, and maintenance scenarios.
- Hybridization and modularity are becoming design priorities. Products that combine power and signaling, or that allow scalable mating configurations, reduce engineering rework and improve downstream adoption.
- Qualification and reliability claims are commercial assets. Especially in aerospace, defense, and harsh industrial settings, certified performance and durable contact systems can justify premium positioning and longer cycle longevity.
- Fragmentation still exists, but targeted consolidation is plausible. The relatively dispersed concentration profile suggests room for acquirers to build scale in particular application verticals, or for specialists to grow through portfolio extension and customer depth rather than broad commodity competition.
The market is not simply becoming more concentrated or more fragmented; it is becoming more application-sliced. Companies that can own a demanding segment end to end—from materials sourcing to qualification to field serviceability—can create defensible positions even in a market where no single player dominates overall share.
Forward Outlook: Three Strategic Themes for 2026 to 2032
Looking ahead, the market's trajectory will likely be shaped less by broad commodity growth and more by where high-current, high-reliability interconnection becomes indispensable. Several themes deserve close attention.
1. Power-dense interconnect demand will keep migrating into new infrastructure layers
As electrification extends deeper into industrial processes, energy storage integration, and large-scale computing environments, the need for connectors that can carry higher current with lower integration risk will continue to rise. The commercial opportunity here is not merely unit volume; it is system-level value. Suppliers that can shorten integration time, simplify maintenance, and support scalable power-signal architectures are more likely to become embedded in customer design standards. The uncertainty is demand pacing: procurement cycles in infrastructure and capital equipment can shift with financing conditions, policy timing, and lead-time realities across the broader supply chain.
2. Materials and regulatory exposure will become design inputs, not afterthoughts
With metals prices elevated and certain material access routes constrained, connector design will increasingly need to account for substitution feasibility, material efficiency, and compliance traceability. This creates opportunities for engineering-led differentiation, such as more efficient contact geometry, smarter plating strategies where permitted, and robust second-source qualification. It also introduces risk: programs tied to single-source materials or slow qualification paths may face cost volatility and schedule fragility. The strategic winners will be those that treat material economics as a design parameter and build sourcing resilience into the product roadmap.
3. Resilience and serviceability will compete with unit cost as purchase criteria
In an environment of unpredictable lead times and elevated materials costs, buyers are likely to weigh total cost of ownership more heavily than headline price. Sealed connectors, vibration-resistant designs, and modular maintenance-friendly architectures can reduce lifecycle friction in industrial and field-deployed settings. For manufacturers, this means product roadmaps should increasingly emphasize durability, service access, and mating reliability as commercial features. For investors, it suggests that value creation may be strongest where companies can command premium positioning through reliability and integration support rather than through volume alone. The key risk is over-indexing on niche durability in price-sensitive segments where standardization and cost pressure dominate.
Industrial Connectors Market
Strategic Actions for Decision-Makers
The current market dynamic rewards preparation over reaction. The most useful moves depend on role, but several priorities apply across the board.
For manufacturers and product leaders
- Prioritize high-current density, hybrid, and ruggedized architectures where integration risk and serviceability drive purchasing decisions. These attributes can support pricing power and longer program life.
- Build material resilience directly into product strategy. Evaluate contact design, plating strategy, and supplier qualification with an eye toward cost volatility and materials-access constraints, rather than treating them as purchasing issues alone.
- Use qualification and reliability messaging as a commercial lever, especially in segments where downtime, maintenance access, and environmental exposure are expensive.
For investors and strategic planners
- Focus on application-specific value pools where power density, reliability, and integration support are difficult to replicate. Broad commodity exposure may understate risk given materials volatility and lead-time unpredictability.
- Watch for consolidation opportunities in segments with strong technical barriers and steady demand, while recognizing that fragmented concentration also supports specialist growth through portfolio deepening rather than scale alone.
- Stress-test assumptions around pricing power. Not all connector lines can pass through materials cost increases evenly, and differentiation quality will determine which players preserve margin.
For procurement and sourcing leaders
- Shift from transactional price negotiations to lifecycle cost evaluation. In applications where downtime and maintenance are costly, sealed, vibration-resistant, or modular connectors may deliver lower total cost even at higher unit price.
- Diversify critical sourcing and qualify second sources where feasible, particularly for materials-intensive or long-lead programs. Supplier allocation volatility makes contingency planning a competitive advantage.
- Align connector specification with future deployment risk. Designs that are easier to service, less sensitive to environmental stress, and compatible with scalable power architectures can reduce retrofit exposure later.
These themes are only the starting point for a full strategic plan. Deeper segmentation detail, regional nuance, application-level demand patterns, and company-specific positioning can materially change how opportunities are prioritized and timed. For decision-makers who need to move from broad trend awareness to executable sourcing, product, or investment choices, more granular market intelligence can help translate these directional signals into concrete next steps.
For detailed analysis of this topic, please visit the official page: Power Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Managed File Transfer Software Market: Why 10.4% CAGR Builds a $3.21B Future
By pmarketresearch, 2026-09-21
Managed File Transfer Software Market: Navigating Compliance, Automation, and the Cloud Shift
A Strategic Outlook on Market Evolution and Commercial Opportunity (2026–2032)
The managed file transfer software market has entered a phase of structural expansion, driven by converging pressures around data sovereignty, enterprise automation, and cloud-native integration architectures. From 2020 through 2025, the total addressable market scaled from approximately 1.1 billion USD to 1.62 billion USD, reflecting sustained adoption across regulated sectors and the gradual migration of legacy file-sharing workflows into purpose-built transfer management platforms. The forward trajectory through 2032 points to a compound annual growth rate of roughly 10.4 percent, with market size expected to reach 3.21 billion USD by the end of the forecast window. This growth is not evenly distributed: it is being shaped by enterprise procurement patterns, regional regulatory divergence, and a rapid pivot from purely on-premise deployments toward hybrid and cloud-based managed file transfer models. For executives and investors, the market represents more than a compliance utility. It is becoming a strategic layer for secure information exchange, partner connectivity, and audit-ready data governance.
The industry is simultaneously confronting several inflection points that will define competitive positioning over the next half-decade. One of the most visible is the tension between legacy architecture expectations and modern cloud delivery models. Many organizations started with on-premise managed file transfer solutions to retain full control over data paths and encryption keys, but the operational burden of patching, scaling, and maintaining infrastructure has accelerated interest in managed and software-as-a-service variants. At the same time, security and compliance requirements are no longer static checklist items. Cross-border data movement is increasingly scrutinized, and enterprises face mounting expectations to demonstrate not only that files are encrypted, but that transfer workflows are auditable, incident-responsive, and aligned with region-specific regulations. Finally, the market is maturing in terms of vendor differentiation. As baseline secure transfer capabilities become table stakes, the winners are those who can reduce manual effort, embed intelligence into workflow orchestration, and integrate managed file transfer into broader integration and data-exchange ecosystems.
Technology Innovation and the Automation Imperative
One of the most consequential drivers of market momentum is the shift from static file movement to automated, policy-driven transfer orchestration. Modern enterprises operate across fragmented partner networks, cloud environments, and internal systems, making manual file exchanges a liability in both speed and risk. Managed file transfer platforms are increasingly expected to act as control planes that encode routing rules, transformation steps, retry logic, and audit trails directly into the transfer workflow. This shift reduces reliance on custom scripts and ad hoc processes, which historically created blind spots in logging and compliance reporting. Recent product activity illustrates the direction of travel. In mid-2025, Progress Software released an updated version of its MOVEit MFT platform with usability enhancements and reinforced security features, signaling continued investment in the core enterprise transfer experience. Shortly afterward, the company introduced a next-generation SaaS automation platform designed to reduce manual processing and infrastructure overhead by up to half, reflecting a broader industry push to make managed file transfer more operationally efficient and less dependent on dedicated administrative staffing.
Worldwide Managed Office Market
Automation is also becoming a competitive differentiator in highly specialized verticals. In media and content supply chains, for example, transfer speed and reliability are essential, and platform vendors are tailoring SaaS-based managed file transfer offerings for high-volume, time-sensitive workflows. Other vendors have focused on visibility and centralized control, launching operations workbenches that unify monitoring and automation across transfer portfolios. These enhancements matter because they change managed file transfer from a backend utility into a managed service layer that can be governed, measured, and optimized. For enterprises, the implication is clear: platforms that embed automation and centralized operational control can reduce operational friction while strengthening governance. For vendors, differentiation increasingly depends on how well automation is packaged, how easily it integrates with existing systems, and how transparent the platform is to security and compliance teams.
Regulatory Pressure and the Compliance-as-Architecture Shift
Regulatory dynamics have become a central force shaping enterprise procurement of managed file transfer solutions. Data transfer compliance is no longer confined to a single framework or jurisdiction. Enterprises operating across borders must navigate a landscape where privacy and data protection expectations differ by region, yet the underlying principle is consistent: cross-border file movement requires demonstrable controls, traceability, and rapid incident responsiveness. Recent enforcement actions and legislative alignment efforts have raised the stakes. In Europe, regulatory attention around data transfer violations has increased organizational sensitivity to how files move across jurisdictions. In other regions, new or updated personal data protection laws are converging toward principles that resemble established global privacy frameworks, expanding the scope of compliance requirements for transfer operations. In parallel, enforcement in jurisdictions with existing data protection regimes has intensified, particularly around cross-border transfers and the consequences of inadequate controls.
This environment is reshaping deployment expectations. Organizations are increasingly seeking platforms that come with pre-configured compliance templates for major standards and regulations, reducing the time and internal effort needed to align transfer workflows with audit expectations. There is also growing preference for real-time logging, automated incident handling, and structured notification capabilities, since these functions can shorten response cycles and help contain the operational and reputational costs of a breach. From a market perspective, this means managed file transfer is increasingly purchased as part of a compliance and risk posture, not solely as a technical integration tool. Vendors that can make compliance easier to demonstrate—through templates, auditable logs, and integration with broader security ecosystems—gain an advantage in regulated sectors such as financial services, healthcare, and government-adjacent enterprises. The strategic implication for buyers is that compliance readiness should be treated as a first-order selection criterion, alongside performance and integration capability.
Demand-Side Shifts and the Hybrid Delivery Model
On the demand side, enterprise behavior is moving toward managed file transfer models that balance control, cost, and scalability. While on-premise deployments still represent a meaningful share of the market, cloud and managed-delivery approaches are expanding as organizations seek to reduce capital expenditure, simplify maintenance, and accelerate deployment. This shift does not imply a wholesale abandonment of on-premise architectures. In many cases, enterprises prefer hybrid arrangements that allow sensitive data paths to remain under direct control while less constrained workflows benefit from cloud elasticity and managed operations. The availability of managed file transfer as a service has made this hybrid thinking more practical by lowering the barrier to entry for organizations that want auditable file flows without building and maintaining full transfer infrastructure internally.
Cost structure and operational accountability are important parts of this transition. Cloud-based managed services can alter the economics of transfer infrastructure by shifting spending from upfront capital investment toward more predictable operational models. They can also improve auditability by standardizing logging, access controls, and administrative workflows. For large enterprises with complex partner ecosystems, these attributes are especially relevant because they reduce the internal burden of maintaining multiple transfer mechanisms across departments and business units. At the same time, procurement teams are increasingly evaluating total cost of ownership through the lens of operational overhead, incident response capability, and integration effort, rather than focusing solely on license or subscription price. This broader evaluation framework favors platforms that can demonstrate measurable efficiency gains and lower ongoing administrative complexity.
Competitive Positioning Among Established and Specialized Players
The competitive landscape includes large platform vendors, specialized transfer vendors, and integration-centric players, each pursuing different angles of differentiation. A useful way to understand the field is to look at how major vendors frame their managed file transfer capabilities within broader portfolios. Some vendors anchor their offerings in enterprise-grade secure transport platforms with strong automation and auditing functions, positioning them for large-scale, controlled file movement across complex environments. Others emphasize secure automation and built-in compliance support, with SaaS-based platforms that aim to simplify deployment and streamline workflow design. There are also vendors whose managed file transfer capabilities are closely tied to broader B2B integration and information exchange networks, making transfer functionality part of a larger connectivity strategy. Cloud-infrastructure vendors contribute another dimension by embedding managed file transfer features into cloud storage and data services, appealing to organizations already committed to a specific cloud ecosystem.
Several specialist and mid-tier vendors are competing on precision, security posture, and vertical fit rather than breadth alone. Some have built their reputation around platform-independent transfer servers with strong compliance characteristics. Others focus on secure-by-design exchange platforms that incorporate threat intelligence or emphasize validated encryption and private data networking. There are also vendors targeting specific industry workflows, such as media, where high-speed secure transfer and automation are especially important, or service-delivery models that emphasize managed transfer as a service with reduced capital expenditure and stronger auditability. This diversity matters because it gives enterprises multiple entry points depending on their priorities: some want a broad, integrated platform; others want a focused, security-first transfer solution; still others want managed services that reduce operational responsibility.
Recent product activity shows how these strategies are being sharpened in practice. Workbench-style operational tooling has been introduced to improve visibility and centralized control across transfer portfolios. Malware-scanning and security-enforcement enhancements have been layered into transfer platforms to address the reality that file exchanges are common vectors for risk. Cloud-based managed offerings have been launched to make deployment faster and more auditable while lowering upfront infrastructure costs. Together, these moves indicate a market that is moving beyond basic secure transfer toward managed, observable, and increasingly automated file exchange services. The competitive trend is not simply consolidation or fragmentation in the traditional sense. Instead, it is a realignment around value propositions: some vendors are extending into broader integration and data exchange platforms, while others are deepening their security, compliance, and automation capabilities to defend specialized positions. New entrants and adjacent platform players continue to find opportunities where they can combine transfer functionality with strong security, workflow intelligence, or industry-specific workflows.
Market Concentration and the Shape of Future Competition
The market remains moderately concentrated, with the largest providers accounting for a meaningful but not dominant share of total revenue. This concentration pattern suggests that scale advantages exist, particularly for vendors with broad enterprise relationships, established integration footprints, and the ability to embed managed file transfer into larger platform deals. However, it also indicates room for specialized players to compete effectively by serving high-value segments where security assurance, compliance readiness, or operational automation is the primary buying driver. As enterprises continue to evaluate managed file transfer as part of wider data governance and integration strategies, vendors with strong cross-functional portfolios may gain from bundling and cross-sell dynamics. At the same time, focused vendors can thrive by offering depth, clarity, and lower operational complexity for use cases where broad platforms introduce unnecessary overhead. The competitive trajectory is likely to favor organizations that can clearly articulate where they provide unique value rather than those that attempt to be everything to every buyer.
Strategic Outlook: Three Trends Shaping 2026–2032
First, managed file transfer will increasingly be treated as a governed integration layer rather than an isolated file movement tool. As enterprises connect partners, cloud services, and internal applications through more orchestrated workflows, transfer platforms will need to interoperate with identity systems, monitoring tools, data-protection controls, and integration pipelines. The commercial opportunity here lies in platforms that reduce friction across the data-exchange lifecycle and make secure transfer part of a repeatable, auditable process. The risk is that fragmented toolchains will persist if buyers select point solutions without sufficient attention to integration and operational unification.
Second, compliance-driven procurement will intensify as data protection expectations continue to diverge and mature across regions. Enterprises will increasingly favor platforms that lower the effort required to demonstrate compliance through templates, logging, incident handling, and controlled data paths. This trend creates durable demand for managed file transfer in regulated industries and raises the premium on vendors who can make compliance evident and operationally manageable. The uncertainty lies in the pace and form of regulatory change, which can differ significantly across jurisdictions and may shift procurement priorities unexpectedly.
PW Consulting
Third, automation and managed delivery will continue to reshape cost structures and operating models. Enterprises will seek solutions that reduce manual administration, improve reliability, and support hybrid deployment preferences. SaaS and managed service models will expand where they can demonstrate clear operational savings and stronger auditability, but on-premise and hybrid deployments will remain relevant where governance requirements or internal policies favor direct infrastructure control. The commercial opportunity for vendors is to offer flexible deployment paths and measurable efficiency gains. For buyers, the challenge is to evaluate whether a given deployment model truly reduces long-term operational burden or merely shifts it.
What This Means for Different Decision-Makers
For enterprise leaders and procurement teams, the priority should be to evaluate managed file transfer as part of a broader secure data-exchange strategy. Selection criteria should go beyond basic encryption and include automation capability, operational visibility, compliance readiness, integration effort, and the practical implications of deployment models for long-term total cost of ownership. Organizations that standardize on transfer platforms with strong auditability and workflow automation are better positioned to manage partner ecosystems and reduce the hidden costs of manual or fragmented file processes. In regulated environments, platforms that make compliance demonstrable through templates, logging, and incident response can materially shorten the path to deployment and lower ongoing risk.
For investors and strategic planners, the market signals a sustained growth trajectory with differentiation emerging around automation, compliance enablement, and managed delivery. Attention should be paid to vendors that can convert operational efficiency into commercial advantage, whether through SaaS-based platforms, workflow-centric automation, or strong integration into wider data-exchange ecosystems. Concentration levels suggest that scale matters, but specialization also remains viable where security, compliance, and vertical fit are valued highly. Monitoring product launches, enterprise adoption patterns, and regulatory developments will be critical for anticipating where competitive advantage is being created and where pricing or positioning pressure may intensify.
For technology and security leaders evaluating build-versus-buy decisions, the most practical path is usually to prioritize platforms that reduce integration complexity and improve governance without locking the organization into unnecessary infrastructure overhead. Managed file transfer should be assessed not only for its immediate secure transfer capabilities, but also for how it supports longer-term objectives such as partner onboarding, audit readiness, automation of repetitive workflows, and alignment with broader integration and data-protection strategies. In practice, the organizations that benefit most are those that treat file transfer as a managed, governed process and select platforms accordingly.
Connecting Market Intelligence to Action
The managed file transfer software market is expanding in both scale and strategic importance, but the value of any decision depends on how clearly the underlying segmentation, deployment trends, regional dynamics, and vendor positioning are understood. Broad market figures provide orientation, but the actionable detail lies in how subsegments evolve, where deployment models are shifting fastest, which compliance and automation capabilities are becoming decisive in enterprise selections, and how competitive positioning is changing across vendor types. Decision-makers who align their strategies with these dynamics are better positioned to capture growth, reduce operational risk, and avoid costly missteps in platform selection or market entry. For those who need a more detailed view of segment-level data, deployment trends, vendor strategy comparisons, and region-specific implications, the full research report provides the granularity required to move from high-level direction to concrete planning.
Software Asset Management Managed Service Market
For detailed analysis of this topic, please visit the official page: Managed File Transfer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com